Need Expert Advice?Our Gurus Can Help

Browse rediffGurus answers related to 'Money' below
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Oct 03, 2026
Money
In 2023 came across a scheme by indusind bank which stated give a deposit of Rs 5 lakh get a medium locker free. Initially the bank staff used to missell the con cept by telling gullible clients that a free medium locker will be then people would give deposit of Rs 5 lakh Infact the scheme is locker rent free for 1st year then 75c/o discount I gave Rs 5 lakh but the locker was not given on writing mails to backend team was told take a small locker later ir was scaled up to 2 i said won't suit me give 1 medium Later on the branch head on behest of DBM said take a insurance plan will give you a large locker rent free. Wen i said scheme is for medium & tommorow if you are transferred it will be a problem for me as the new branch head will ask for full rent he said will tell him not to do Under duress & pressure i went for the offer took the plan on realising i have been fooled i called the custcare of icici life ins for return of policy under free look period they in turn informed the bank agent who passed on the info to branch head who persuaded me to keep the policy i had to keep quiet. I was made to visit several times then told loc ker not there lateron was told searching vacant locker in other branch will give you there thinking this offer will be refused i said ok that also didn't happen Again i called custcare was told sent a mail i did still no reply lateron was told your mail id is not registered with us first hence mails not considered. Then i completed this formality sent them a fresh mail for policy cancellarion was told free look period over hence request can't be entertained Went to the branch office in B-1 janakpuri delhi wrote mails but of no avail i stopped paying further premiums. Got several mails SMS asking me to give bank + personal details for moneyback i said it's a missell case want policy premium paid refund was denied by icici stating freelook period over. The bank backend team of indusind was of no help either. The seniors at bikhajicama place office of indusbank also didn't help me out. This year on insistence i sent them my details but was told imoroper so moneyback can't be processed another mischeif by bank seniors I highlighted this issue with bank seniors + ins company but all in vain nobody paid heed As my details were incomplete my cashback after initial display was given of 1 year the 2 nd year moneyback is unpaid. As this is a clearcut case of missell by indus ind bank vikaspuri branch seniors the icici company agents are not responsible in any way they acted on behest of branch seniors Kindly look into the matter help me out by getting pending cashback + the initial first premium paid amount The indusbank branch senior staff & the com pany officials must be reprimanded for their misseeds as mine is not an isolate case there are others also suffering at these people hands Thanking you Deepak verma
Ans: The key issue is not simply non-allotment of a locker. It is the alleged linking of a banking facility with an insurance purchase, followed by repeated assurances and difficulty in getting the promised benefit.

If the facts are supported by documents, this should be treated as a formal mis-selling and deficiency-of-service grievance.

» Keep the two issues separate

There appear to be two connected but separate matters:

– The promised medium/large locker facility against the banking relationship.

– The insurance policy that you say was purchased only because of pressure and assurances from branch officials.

This distinction is important. The insurance company may take the position that the policy was issued after completion of its own proposal and free-look process. Your grievance against the bank, however, can separately concern what was represented to you by its employees and whether the insurance purchase was induced by a promise relating to the locker.

» Build a proper documentary record

Please collect and preserve:

– Original advertisement/circular or written communication regarding the Rs.5 lakh deposit and locker facility.

– Deposit/account records showing when the Rs.5 lakh was placed.

– All emails exchanged with the branch, backend team and senior officials.

– SMS messages and other communications relating to the locker.

– Insurance proposal form, policy document, premium receipts and cancellation correspondence.

– Your emails requesting cancellation during the free-look period.

– Any complaint numbers generated by the bank or insurance company.

– Communications concerning the later cashback/moneyback facility.

– Details of the branch officials who made the representations, as far as available.

– A chronological record of every important visit and conversation.

The chronology you have already provided is useful. Put it into a simple date-wise This can make your grievance much stronger.

» The free-look argument needs careful examination

The insurance company may focus only on whether your cancellation request was received within the applicable free-look period.

Therefore, the important question is not merely:

“Did I cancel after the free-look period?”

It is also:

“Did I attempt to cancel within the free-look period, and was that attempt prevented, delayed or interfered with because of the conduct of the bank staff?”

If you have evidence of an earlier call, email, complaint or other communication, preserve it carefully.

If the first cancellation request was actually made within the applicable period, but the matter was subsequently delayed because you were persuaded by the branch officials to continue with the policy, that fact should be clearly highlighted in your grievance.

» Do not make the insurance company the only target

Based on your narration, your primary grievance appears to be against the bank officials who allegedly represented that purchasing an insurance policy would result in a larger locker being provided.

So your complaint should clearly state:

– What was originally promised.

– What actually happened.

– What the branch officials subsequently offered.

– Why you purchased the insurance policy.

– When you first tried to cancel it.

– What response you received.

– How the matter continued thereafter.

This gives the matter a much clearer structure than simply asking for a refund of the insurance premium.

» Escalate through the formal grievance mechanism

Since you have already approached branch officials and senior bank personnel, the next step should be a properly documented complaint through the bank's formal grievance/redressal mechanism.

Similarly, raise a separate written grievance with the insurer regarding the insurance policy.

Do not depend only on telephone conversations. Written complaints with acknowledgement are much more useful.

If the bank does not resolve the grievance after exhausting its internal complaint process, you can consider approaching the RBI's complaint mechanism, subject to the applicable eligibility and jurisdiction.

For the insurance-related grievance, the insurer's internal grievance mechanism should first be exhausted, followed by the applicable insurance grievance redressal route if the matter remains unresolved.

» About the pending cashback

This needs separate verification.

If the cashback was contractually payable under the insurance policy and you have satisfied the applicable conditions, ask the insurer to provide a written reason for withholding the second year's amount.

Ask them to specify:

– The exact policy condition under which payment was stopped.

– Which customer detail was allegedly incomplete or incorrect.

– When you were informed about this deficiency.

– What documents are required to rectify it.

– Whether the first year's payment was made under the same conditions.

This forces the matter to move from verbal explanations to a specific contractual response.

» Be careful about the remedy you demand

I would not make only a general request that the officials be reprimanded.

Your complaint should first seek specific relief:

– Payment of any legitimate pending cashback.

– Review of the premium paid, considering the alleged inducement and the circumstances in which the policy was purchased.

– Written explanation from the bank regarding the locker representations.

– Written explanation regarding the role of the branch officials.

– Appropriate compensation/redressal, if supported by the facts and applicable grievance mechanism.

Disciplinary action against employees is ultimately for the institution or regulator to decide based on the findings. Your complaint will be stronger if it concentrates on facts, evidence and the specific financial loss suffered.

» 360-degree assessment

From an investment professional and AMFI-Registered MFD perspective, I would also suggest one broader lesson.

Banking products, insurance products and investment products have different purposes. A customer should not be pushed into an insurance policy merely because another banking facility is being discussed.

Whenever a bank employee links one product with another benefit, ask for the offer in writing before making any payment or signing any proposal.

In your case, the most important thing now is not to lose hope. You have a detailed sequence of events, and that can be converted into a strong documentary grievance.

» Finally

Your case should be presented as a documented sequence of alleged mis-selling, inducement, failure to provide the promised banking facility, attempted cancellation of the insurance policy, and subsequent non-payment of the claimed cashback.

Avoid emotional or very strong allegations unless you have documentary evidence supporting them. Use words such as “represented”, “assured”, “alleged”, “requested”, “refused” and “not provided”. This makes the complaint more precise and credible.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188
www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Oct 03, 2026
Money
I have purchased jeevan saral policy Rs 4083 per month for 15 years in Oct 2011 at the age of 52 years. What will be the maturity amount. Thanks
Ans: The exact maturity amount cannot be determined from the monthly premium alone. For Jeevan Saral, the entry age, policy term, maturity sum assured and applicable Loyalty Addition are important.

» Your policy details

You have mentioned:

– Entry age: 52 years
– Policy commencement: October 2011
– Monthly premium: Rs.4,083
– Premium-paying term: 15 years
– Expected maturity: around October 2026

Jeevan Saral provides maturity benefit based on the applicable Maturity Sum Assured, along with Loyalty Addition, if applicable.

» Why I cannot give an exact figure

For Jeevan Saral, the maturity benefit is not simply the total premiums paid.

The applicable Maturity Sum Assured depends on the policy details, including the entry age and policy term. Loyalty Addition, if applicable, is also added at maturity.

Therefore, giving you one exact maturity figure based only on Rs.4,083 monthly premium could be misleading.

» What you should check

Please look at your original policy bond and give me these 4 details:

– Plan No.

– Policy term.

– Sum Assured / Maturity Sum Assured.

– Date of maturity.

You can also upload a photo or PDF of the first page of the policy bond after hiding your policy number, address and other personal details.

Once you provide these details, I can help you work out the likely maturity amount, including the applicable Loyalty Addition, as far as the available policy information permits.

Since your policy is reaching maturity now, I would also suggest obtaining the maturity quotation directly from LIC before making any decision about reinvestment.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188
www.holisticinvestment.in
https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Oct 01, 2026
Money
SIR I AM A 56 YEAR OLD MAN AND A FINANCIAL ASSETS IN FORM OF URBAN LAND HAVING A MARKET VALUE OF Rs 25 CRORES MY MONTHY EXPENSIS ARE 1.5 LAC ONE DAUGHTER MARRIED NO OTHER LIABILITY A HEALTH COVER OF 2 CR SHOULD I SELL THE LAND AND INVEST IN BETTER RETURS INSTRUMENT THE PROPERTY GROWS AT 5 % ANNUALY
Ans: You have a very strong asset base, with urban land valued around Rs.25 crores, no major liabilities, monthly expenses of about Rs.1.5 lakh, and your daughter already married.

At age 56, the main question is no longer only about creating wealth. It is about converting part of your wealth into liquidity, regular income and better diversification.

» Do not sell the entire land immediately

I would not suggest selling the entire Rs.25 crore property simply because it is growing at around 5% annually.

Land has some advantages:

– It is a tangible asset.

– There is no fund-management risk.

– A good urban location can sometimes see substantial value appreciation over a longer period.

– It can provide a useful legacy asset.

But having almost the entire financial wealth in one land asset also creates concentration and liquidity risk.

The property may be worth Rs.25 crores, but it does not automatically provide monthly cash flow for your expenses.

» Your income requirement is relatively small

Your stated monthly expense is Rs.1.5 lakh, which is around Rs.18 lakh a year.

Against an asset base of Rs.25 crores, this is a relatively modest spending requirement.

Therefore, there is no need to take a drastic decision and liquidate the entire property.

A more balanced approach would be to consider whether a part of the land can be monetised and gradually moved into a diversified financial portfolio.

» Compare 5% property growth properly

Your present property appreciation of around 5% is not the same as a guaranteed 5% return.

There are also costs connected with holding and selling property, including maintenance, transaction costs and taxation.

At the same time, financial investments also carry market and interest-rate risks. So it would not be correct to assume that selling the land and putting the entire amount into financial products will automatically produce a higher return.

The objective should be diversification rather than simply chasing a higher return.

» A phased approach may suit you

Instead of selling the complete property at one time, you can consider:

– Retaining a meaningful portion of the land as a long-term asset.

– Selling only a portion if the valuation and buyer opportunity are attractive.

– Moving the sale proceeds gradually into a diversified portfolio.

– Keeping a separate liquid reserve for several years of expenses.

– Creating a regular income stream from the financial portfolio.

– Keeping sufficient growth-oriented investments for your long retirement period.

This can give you both property exposure and financial liquidity.

» Important tax consideration

Before selling the land, please get the capital-gains position calculated by a tax professional.

Land held for more than 24 months is generally treated as a long-term capital asset. Current tax rules provide for 12.5% LTCG taxation in applicable cases, but the exact tax treatment depends on the acquisition date, transfer date, cost and other facts.

For a property of this size, tax planning before the sale is very important.

Do not sell first and think about taxation later.

» Your age makes liquidity important

At 56, you could potentially have several decades of retirement ahead.

Therefore, I would give more importance to:

– Liquidity

– Regular income

– Capital preservation

– Diversification

– Growth to beat inflation

– Estate planning

Your Rs.2 crore health cover is also a positive part of your overall financial protection.

» One more important point

Please do not move Rs.25 crores into one financial product or one category just because somebody promises a higher return.

The portfolio should have different roles.

Some money should provide stability and liquidity.

Some money should generate regular income.

Some money should provide long-term growth.

Some portion can remain in the property if you are comfortable holding it.

» Final Insights

You are not in a position where you need to sell the land urgently to meet your expenses.

Your stronger opportunity is to convert your concentrated wealth into a more balanced structure over time.

If the land is genuinely appreciating only around 5% and represents almost your entire wealth, partial monetisation deserves serious consideration.

However, I would not recommend selling the entire Rs.25 crore holding without first examining the purchase cost, present market value, exact location, rental or development potential, tax implications and your desired inheritance for your daughter.

A proper 360-degree review can then decide how much property to retain, how much to liquidate and how the financial assets can be structured for income, growth and capital preservation.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188
www.holisticinvestment.in
https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Oct 01, 2026
Asked by Anonymous - Sep 30, 2026
Money
I am facing the same problem with Finsol Securities Pvt Ltd as this user faced it in the past. Can you help me what to do. Can you provide me the details of the user so that I can ask the user what he has done in this situation. I am quoting his question and your answer for reference. This question was "Asked by Anonymous on Jul 19, 2026" "I am an investor in Finsol Securities Pvt. Ltd. SEBI Reg. No. INZ000328134. I have invested in securities, IPOs and Mutual Funds as per their announcement in whatsapp, & wen portal. Regret to say even after two months still I didn't get my Trade Code and compliance as per SEIB regulation. For withdrawal of funds in my account they demand service fee in advance. After maturity of Mutual Fund, it goes to my account with them. Is it correct? How to confirm with SEBI. Ans: Several things you mentioned are classic warning signs of unregistered or fraudulent investment schemes: No Trade Code / Client ID issued after two months. Every SEBI-registered broker must issue you a Unique Client Code (UCC) at account opening, not months later. This delay alone is a serious red flag. Demanding a "service fee" before releasing your own funds. This is not standard practice anywhere in Indian regulated markets. Legitimate brokers deduct fees/brokerage automatically from your account or trade proceeds — they never ask you to pay extra money upfront just to withdraw what's already yours. This pattern (pay more to get your money out) is very commonly seen in fraudulent trading platforms. Mutual Fund maturity proceeds going into "your account with them" instead of your own bank account. In genuine mutual fund investing, redemption proceeds go directly to your registered bank account via NACH/RTGS — never held or routed by an intermediary into some internal wallet or account they control. Investment solicitation over WhatsApp and a "wen portal" (unofficial web portal). SEBI-registered entities are not supposed to solicit or manage investments through unofficial WhatsApp groups or unrecognized web portals. This is a very common pattern in "pump and dump" or fake broker scams currently active in India."
Ans: You have done the right thing by checking this before sending any further money.

The SEBI registration number quoted in the earlier question, INZ000328134, is associated with Finsol Securities Private Limited. The important point is not only whether the entity is registered, but whether the person, WhatsApp group, website or platform dealing with you is genuinely acting through the registered entity and following the proper process.

» About the previous user

I cannot provide you with the personal details, identity, contact number, email ID or other private information of the anonymous user who posted that question.

The question was posted anonymously, and it would not be appropriate to try to identify or contact that person through private information.

You can refer to the publicly available question and answer itself. More importantly, your own case should be handled independently, based on your documents and transaction records.

» Your immediate priority

If you are also being asked to pay a "service fee", "release fee", "withdrawal fee", "tax", "security deposit" or similar amount before your own money can be withdrawn, I would be very cautious.

Do not send any further money merely because somebody tells you that paying this amount will release your existing funds.

Ask them in writing to provide:

– Your UCC / client code.

– Your complete account opening and KYC documents.

– Your ledger statement.

– Contract notes for all trades.

– Details of securities actually held in your demat account.

– Mutual fund transaction statements directly from the relevant mutual fund / registrar.

– A proper written explanation for the withdrawal restriction.

– The exact agreement or tariff document under which the additional fee is being demanded.

Keep screenshots of WhatsApp conversations, payment requests, bank details, receipts, portal balances and all emails.

Do not delete anything.

» Very important verification

The registration number alone does not prove that the particular WhatsApp person, website or payment account you are dealing with is genuine.

Therefore, compare the following very carefully:

– Legal name on your documents.

– SEBI registration number.

– Exchange membership details.

– CDSL / NSDL demat details.

– Bank account into which you paid money.

– Name of the beneficiary on that bank account.

– Email domain used by the person dealing with you.

– Website/app through which you were asked to transact.

– Your actual UCC and demat account.

Any mismatch deserves immediate attention.

» Mutual fund money

I would also correct one part of the earlier answer you quoted.

It is too broad to say that mutual fund redemption proceeds can never pass through an intermediary in any circumstance. The exact process depends on how the investment was made and the intermediary arrangement.

But you should be able to independently verify the mutual fund units and transactions through the appropriate official records.

Do not rely only on a balance shown inside a private portal.

Ask for your actual mutual fund folio numbers and transaction statements. Verify that the units genuinely exist in your name.

Similarly, for shares, check your actual demat holdings independently rather than relying only on the trading portal balance.

» If you have already paid money

If you have already transferred money and are now unable to withdraw it, please do not make another payment simply to "unlock" the account.

Prepare one folder containing:

– All payment proofs.

– Bank statements.

– Screenshots of the portal.

– WhatsApp chats.

– Names and mobile numbers of people who contacted you.

– Email communications.

– UCC/client account details.

– Contract notes and statements, if any.

– Mutual fund statements, if any.

– The demand for the additional service/release fee.

This documentation will be very useful when making a formal complaint.

» SEBI complaint route

SEBI's SCORES system allows investors to lodge complaints against SEBI-registered intermediaries.

Generally, you should first approach the concerned entity through its grievance mechanism and ask for a written response.

There is also a distinction between a genuine grievance against a registered intermediary and a situation where somebody may be misusing the name or registration of a genuine intermediary.

If you suspect that an unauthorised person or platform is collecting money by using the name of a registered entity, mention this clearly in your complaint.

» Do this before making the complaint

Write to the broker's official compliance/grievance contact and ask for a written response.

Do not depend only on the WhatsApp person who is handling your account.

Ask them to confirm:

– Whether you have a valid client/UCC account.

– Whether the money you deposited is reflected in your client ledger.

– Whether the securities shown in your portal are actually held in your demat account.

– Why withdrawal is restricted.

– The contractual or regulatory basis for any additional payment demanded.

Keep a copy of your complaint and their response.

» If you want to contact the previous questioner

Unfortunately, I cannot give you the anonymous user's personal details.

But you do not need that person's experience to establish what has happened in your case. Your own bank records, demat statement, mutual fund statement, UCC, contract notes and communications will provide much stronger evidence.

SEBI also provides investor grievance and helpline facilities which you can use to clarify the appropriate complaint route.

» Final Insights

The fact that Finsol Securities has a SEBI registration does not, by itself, establish that every person, WhatsApp group, payment account or website using the Finsol name is authorised.

So please do not panic, but also do not send additional money merely because you are told that it is necessary for withdrawal.

If you give me the following details from your case, with PAN, account numbers, mobile numbers and other personal information removed:

– How much you deposited.

– How you deposited it and whose bank account received it.

– What investment was shown in the portal.

– Whether you have received a UCC.

– Whether you have a demat statement.

– Whether you have contract notes.

– What amount they are asking you to pay now.

– The exact reason they gave for the payment.

– Whether you can see the securities in your actual demat account.

I can help you assess the situation step-by-step and prepare a proper complaint representation.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188
www.holisticinvestment.in
https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 29, 2026
Money
Cani discontinue the premium payment after 2 year
Ans: » Need to Check the Policy Type

Yes, in some insurance policies, you may be able to discontinue premium payments after 2 years. But you should not stop paying without checking the exact policy conditions.

The outcome depends mainly on the type of policy, premium-paying term and policy terms.

» What Can Happen If You Stop

Depending on the policy, stopping premiums may result in:

– The policy becoming paid-up with reduced benefits.

– The policy getting discontinued or lapsing.

– A surrender value becoming available.

– The policy continuing with certain reduced benefits.

– A revival option being available later, subject to conditions.

So, simply completing 2 years does not mean that stopping the premium is always the right option.

» Check These Before Discontinuing

Please check:

– Name of the policy and plan.

– Premium-paying term.

– Total policy term.

– Premium amount and frequency.

– Current surrender value.

– Paid-up value after stopping premiums.

– Life insurance benefit that will continue after discontinuation.

» If It Is an Investment-Cum-Insurance Policy

If this is an investment-cum-insurance product, do not take the decision only because you have completed 2 years.

Compare the financial outcome of continuing, making the policy paid-up, or surrendering it, after considering the benefits already accumulated and the applicable charges.

If the policy is unsuitable for your financial goals, a review can be done before committing further premiums.

» Final Insights

You can potentially discontinue premiums after 2 years, but whether you should do so is a separate question.

Please share the policy name, annual premium, policy term and premium-paying term. If you also share the amount already paid, I can explain the likely options available to you in simple terms.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 29, 2026
Asked by Anonymous - Sep 28, 2026
Money
student i am 20 and non professional with saving and want to invest in mutual fund and aggressive invest and my allocation smallcap , theme,sectoral fund no dedt fund and index , style is active fund only ?
Ans: At 20, having started thinking about investing early is a strong positive. The main focus should now be building the right structure, not simply taking maximum risk.

» Your Proposed Allocation

I would not suggest putting the entire portfolio into small-cap, thematic and sectoral funds.

These categories can be aggressive, but aggressive does not automatically mean better long-term investing.

Sectoral and thematic funds have higher concentration risk because they are restricted to particular sectors or themes.

» A Better Aggressive Approach

For a 20-year-old with a long investment horizon, an equity-heavy portfolio can be considered, provided you can handle large temporary falls without stopping your SIPs.

A diversified structure can include:

– A core allocation through actively managed diversified equity funds.

– A meaningful allocation to mid-cap and small-cap funds.

– A limited allocation to thematic or sectoral funds.

– Debt is not compulsory for every young investor, but some emergency money should remain outside equity.

The key word is diversified.

» Small-Cap Funds

Small-cap funds can provide higher growth potential over a long period, but they can also experience sharp corrections.

Therefore, I would not make small-cap your entire portfolio.

Use it as one part of an aggressive portfolio rather than the complete portfolio.

» Sectoral And Thematic Funds

I would keep this allocation limited.

A sector can remain out of favour for several years. A theme can also take longer than expected to deliver.

You are making a concentrated bet when you choose these categories. So they should be a satellite portion of the portfolio, not the foundation.

» Active Funds Instead Of Index Funds

If your preference is active investing, actively managed funds can certainly be considered.

However, do not select an active fund merely because it has recently beaten an index.

Look at:

– Consistency across market cycles.

– Fund manager experience and investment process.

– Portfolio diversification.

– Risk taken to generate returns.

– Expense ratio.

– Portfolio overlap with your other funds.

» No Debt Fund

At age 20, with a genuinely long investment horizon, having a high equity allocation can be reasonable.

But keep your emergency money separately in suitable low-risk and easily accessible instruments.

Do not put money needed for education, emergencies or other near-term requirements into aggressive equity funds.

» Regular Funds Through MFD

If you invest through an MFD, regular plans can provide ongoing service such as portfolio reviews, asset-allocation checks, rebalancing and goal-based guidance.

Direct plans have a lower expense ratio, but you have to manage fund selection, monitoring and rebalancing yourself.

So the choice should depend on whether you want to manage the portfolio yourself or want ongoing support through an MFD.

» Final Insights

At 20, your biggest advantage is time.

Do not try to maximise risk. Try to maximise the number of years you remain invested.

An aggressive portfolio can be mostly equity, but I would avoid making it entirely small-cap, sectoral and thematic.

Build a diversified core first. Then add small-cap and limited thematic/sectoral exposure around it.

Most importantly, continue investing regularly during market falls. That discipline can matter more than finding the perfect fund.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 26, 2026
Money
I invested Rs. 17000 in digital gold in the month of February 2026 when the gold was rallying northward with the hope of making some quick bucks but since then it has always remained in the negative with no signs of upward movement. What should I do now. Shall I stay put or I should come out it because even the PM has requested not to purchase gold even during the upcoming wedding season.
Ans: It is good that you are reviewing the decision instead of reacting only to the current negative return.

Your original purpose was to make quick money from a rising gold price. That is important. Gold is generally better treated as a diversification asset, not as a short-term trading instrument.

Also, the recent fall does not mean that gold has permanently lost its value. Gold prices had a sharp rally earlier in 2026 and have also seen a meaningful correction and volatility since then.

» About the PMs Statement

Yes, Prime Minister Narendra Modi recently appealed to Indians to avoid buying gold unless it is necessary. The context was reducing discretionary imports and promoting domestic spending and self-reliance.

However, this should not be treated as a direct investment call to sell your existing gold.

There is a difference between:

– A policy appeal to reduce unnecessary gold purchases.

– An investment decision about an amount you have already invested.

So I would not sell merely because of that statement.

» The Bigger Issue: Digital Gold

There is another important point in your case.

SEBI has cautioned investors about digital gold products offered through online platforms. Such products are outside SEBI's regulatory framework and may involve counterparty and operational risks.

The investor-protection mechanisms applicable to SEBI-regulated securities are not available for such products.

Therefore, your decision should not be based only on whether your Rs.17,000 is currently showing a loss.

You should also ask:

– Why am I holding digital gold?

– Is the platform and product structure suitable for long-term holding?

– Was the investment intended for short-term trading or diversification?

» What I Would Do

Since the original intention was quick profit, I would not continue holding it simply with the hope that it will soon recover.

If you have no specific long-term requirement for gold, you can consider exiting the digital gold and redirecting the money towards a properly planned investment aligned with your goals.

At Rs.17,000, the bigger lesson is more important than the current profit or loss.

Avoid making investment decisions based on recent price momentum. Gold was rising sharply when you bought it, which probably influenced the decision. The same emotion can now make you hold it because you want to recover the loss.

Both decisions are driven by the market price rather than your financial goal.

» If You Still Want Gold Exposure

If gold is part of your overall asset allocation, it can have a role as a diversification asset.

But I would prefer a regulated investment route rather than accumulating digital gold merely for price speculation. The important point is to decide the appropriate allocation first and then select the investment vehicle.

Do not keep adding money just because the price has fallen.

» 360-Degree View

For your overall financial plan, I would look at:

– Emergency fund and liquidity.

– Life and health insurance adequacy.

– Existing equity and debt investments.

– Gold exposure, including physical and digital gold.

– Near-term financial goals.

– Retirement requirements.

– Tax impact before selling any investment.

– Whether the investment is being made for a goal or merely for a quick return.

The Rs.17,000 itself is not likely to materially change your financial future. The investment behaviour you develop from this experience can.

» Final Insights

I would not sell digital gold merely because the PM has advised against unnecessary gold purchases.

But I also would not hold it indefinitely just to recover the current loss.

Since your original objective was quick profit, reassess that objective first. If you no longer have a reason to hold digital gold, exiting and moving towards a goal-based, diversified investment plan can be considered.

Most importantly, dont chase a rising asset after a rally. Decide the purpose and allocation first, then invest.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 25, 2026
Money
Hi Sir, I got a gold about 30gms which we got as gift for my son on his 1st birthday form his grand parents and relatives. I and my wife thought to sell that gold and invest that liquid amount in FD or any other cashflow instrument for his education purpose. As we admitted him in good pvt school going forward we feel that it will be difficult for us to afford his education. I would like to know your view on this.
Ans: It is a thoughtful decision to use an asset received for your sons future education. At the same time, I would not rush to sell the gold only because school expenses may increase.

» Purpose of the Gold

– The 30 grams of gold was received as a family gift for your son. So it has both financial and emotional value.

– Gold can also act as a long-term asset and need not be treated as an idle investment.

– Before selling, discuss with your wife whether you are comfortable converting this family gift into an education corpus.

» Should You Sell the Gold?

– If the gold is jewellery, selling it may involve making charges and other deductions. The amount received may therefore be lower than the current market value of the gold.

– If you do not have adequate emergency savings, selling the gold and keeping the entire amount in an FD may not be the best use of the money.

– However, if your emergency fund is already comfortable and you have a clear education goal, converting part or all of the gold into a financial investment can be considered.

– The key point is not gold versus FD. The key question is how much money you need for your sons education and when you will need it.

» FD or Growth-Oriented Investment?

– If the education requirement is very close, capital safety becomes more important. FD or other suitable fixed-income options can have a role.

– If your son is still very young and the education goal is many years away, you have more time to use growth-oriented investments.

– For a long-term education goal, a combination of equity-oriented mutual funds and safer fixed-income investments can be considered.

– Do not put the entire education corpus into equity. As the education date comes closer, gradually reduce the exposure to market-linked assets.

» Build the Education Corpus Separately

– Your regular monthly SIP should ideally continue for retirement and other long-term goals.

– Create a separate education corpus for your son.

– The gold sale proceeds, if you decide to sell, can become the initial contribution to this corpus.

– Going forward, even a small monthly SIP dedicated only to education can make the plan stronger.

– As school fees rise over the years, review the education corpus once every year and increase the contribution whenever your income improves.

» Do Not Depend Only on FD

– FD gives stability and predictable interest, but long-term education costs can rise faster than the return available after tax.

– Therefore, using only FD for a very long education goal may reduce the growth potential of the corpus.

– A mix of growth assets and safer assets can provide better balance between growth and capital protection.

» 360-Degree Financial Check

– Before using the gold, first ensure you have an adequate emergency fund.

– Check that health insurance is sufficient for the family.

– Ensure adequate term insurance for the earning members.

– Keep retirement planning separate from your sons education planning.

– Avoid taking large loans later only because education expenses were underestimated today.

» My View

– If your son is still many years away from higher education, I would not sell the gold merely to put the money into an FD.

– If you are comfortable emotionally with selling the gift and your emergency fund and insurance are already in place, the gold can be converted into a dedicated education corpus.

– The better approach is to combine the initial corpus with regular monthly investments and review the goal every year.

– Most importantly, do not allow the good private school expense to disturb your retirement savings. Your sons education and your retirement need to be planned together.

» Final Insights

– The 30 grams of gold is a useful starting asset, but it need not carry the entire education burden.

– With disciplined monthly investing, increasing contributions as income grows, and gradually moving towards safer assets when the education date approaches, you can build a meaningful education corpus.

– A goal-based review will give you much better clarity than simply choosing between gold and FD.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 22, 2026
Asked by Anonymous - Sep 20, 2026
Money
Aditya Birla Sun Life Flexi Cap Fund (G) 5000 Kotak Emerging Equity Scheme - Regular Plan (G) 3000 Mirae Asset Large & Midcap Fund - Growth 10000 Nippon India Small Cap Fund (G) 3000 Bandhan Small Cap - Direct 3000 Parag Parikh Flexi Cap Fund - Direct - 5000 HDFC Balance Advantage Fund - Direct 10000 ICICI Prudential Nifty IT Index Fund - Direct 1000 total sip is 40K per month, current portfolio is 13L, target 2cr in 10-12 years, plz review my portfolio and suggess
Ans: You have already built a good base with around Rs.13 lakh and a Rs.40,000 monthly SIP. A 10–12 year horizon gives you enough time to work towards a Rs.2 crore goal, but the portfolio needs some simplification and better diversification.

» Your present portfolio

Your Rs.40,000 monthly SIP is spread across:

– Flexi-cap category: Rs.10,000

– Large & mid-cap category: Rs.10,000

– Small-cap category: Rs.6,000

– Balanced Advantage category: Rs.10,000

– IT sector index category: Rs.1,000

– Another flexi-cap allocation: Rs.3,000

This is not a bad collection of categories, but there is some duplication.

You have two flexi-cap funds, two small-cap funds and separate IT sector exposure. For a Rs.13 lakh portfolio, having too many funds can make monitoring difficult.

» The main issue I see

Your portfolio has a strong equity orientation, which can be suitable for a 10–12 year goal.

However, the portfolio is slightly complicated for the amount invested.

The objective should not be to own many funds. The objective should be to create a portfolio where every fund has a clear role.

Your portfolio can be made much cleaner with:

– One core flexi-cap allocation.

– One large & mid-cap allocation.

– One small-cap allocation.

– One balanced/hybrid allocation.

That can be enough for the core portfolio.

» Small-cap allocation

Your small-cap SIP is Rs.6,000 out of Rs.40,000.

That is around 15% of the monthly SIP.

This is a reasonable range for a long-term investor if you can tolerate sharp temporary falls.

But you already have mid-cap exposure through the large & mid-cap allocation. So there is no need to increase small-cap exposure aggressively.

Small-cap funds can experience deep corrections. Keep this allocation only if you can continue the SIP during bad markets.

» IT sector exposure

The Rs.1,000 monthly IT sector allocation is small, so it will not dominate the portfolio.

Still, I would not make a sector-specific index fund a core part of a Rs.2 crore retirement/wealth goal.

A sector index simply follows the selected sector. It does not have the flexibility of an actively managed fund to reduce exposure when valuations or business conditions become unattractive.

For a long-term wealth goal, diversified actively managed funds can provide wider sector diversification and the fund manager can change the portfolio based on changing business conditions.

If you like IT as a satellite exposure, keep it small. But it should not become a major part of your overall portfolio.

» Direct and regular plans

You are currently holding both direct and regular plans.

The important point is not to select direct plans only because the expense ratio is lower.

Direct plans can work for investors who are comfortable doing their own fund selection, monitoring, rebalancing, taxation and goal-based asset allocation.

Regular plans through an AMFI-registered MFD have an additional distribution cost, but you get ongoing service, portfolio monitoring and help with rebalancing and goal alignment.

Since your objective is Rs.2 crore and the portfolio has multiple categories, having a proper review process can be more important than simply looking at the lower expense ratio.

Do not switch from regular to direct or vice versa purely based on recent returns.

» Can Rs.2 crore be achieved?

Your present Rs.13 lakh corpus is a useful starting point.

Your Rs.40,000 monthly SIP is also meaningful.

But for a Rs.2 crore target in 10–12 years, the SIP should not remain fixed at Rs.40,000 for the entire period.

Your plan to increase investments with income growth will be very important.

I would strongly suggest an annual SIP step-up.

Instead of trying to predict the exact return required, focus on:

– Increasing SIP every year.

– Staying invested through market corrections.

– Avoiding unnecessary fund switching.

– Keeping the portfolio diversified.

– Reviewing the asset allocation once or twice a year.

This gives you a much better chance of reaching the target.

» How I would structure the portfolio

Without using specific scheme names, I would keep the core portfolio around four categories:

– Diversified flexi-cap: core equity allocation.

– Large & mid-cap: additional growth exposure.

– Small-cap: limited satellite allocation.

– Balanced Advantage: stability and some dynamic asset allocation.

The exact percentage should depend on your age, income stability, other investments and whether Rs.2 crore is a compulsory goal or an aspirational target.

I would remove unnecessary duplication rather than keep adding more funds.

» What to do with the existing Rs.13 lakh

Do not redeem everything and restart the portfolio.

That can create unnecessary taxation and transaction issues.

Instead:

– Stop fresh SIPs in categories that are duplicated.

– Gradually redirect new SIP money towards the chosen core categories.

– Review existing holdings before deciding whether any switch is required.

– Avoid switching merely because one fund has performed better recently.

This can make the transition smoother.

» The 10–12 year goal needs stages

There is another important point.

If Rs.2 crore is required at the end of 10–12 years, you should not remain fully aggressive right up to the target date.

Around 3–5 years before the goal, gradually start moving the money required for the goal towards relatively stable assets.

Otherwise, a major equity correction just before the goal can disturb the entire plan.

» Tax planning

When you eventually redeem equity mutual funds, current rules need to be considered.

Equity mutual fund LTCG above Rs.1.25 lakh in a financial year is taxed at 12.5%.

STCG is currently taxed at 20%.

Therefore, future withdrawals should also be planned in a tax-efficient manner rather than redeeming a large amount without planning.

» Final Insights

Your portfolio is not fundamentally bad. The bigger issue is that it has more moving parts than necessary.

With Rs.13 lakh already accumulated, Rs.40,000 monthly SIP and 10–12 years available, you have a good base to build on.

My focus would be:

– Simplify the number of funds.

– Keep one core flexi-cap allocation instead of unnecessary duplication.

– Keep small-cap exposure controlled.

– Keep IT sector exposure small.

– Use diversified actively managed funds as the core.

– Increase the SIP every year.

– Review asset allocation regularly.

– Start protecting the corpus gradually as the Rs.2 crore goal approaches.

The most important missing information is your age, present income, existing EPF/PPF/NPS/FD investments and whether Rs.2 crore is needed for a specific goal. These details can materially change the ideal allocation.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 22, 2026
Asked by Anonymous - Sep 21, 2026
Money
Hello Sir I am a 43 year old pvt sector employee. I currently am investing 55k pm via sip in large/mid/small/ defence index/nifty 50 and next 50 and hold an aggregate MF portfolio of around 46 lakhs of which around 7 lakhs is in Debt, Money Market and Arbitrage funds. I plan to increase the said allocation by min 15% every year. I also invest 15k pm in Gold in a reputed jewellery chain. My monthly investment in NPS is 9k which would be increased next year. Annual Ppf works out to 60-75k. My EPF accumulated balance is 50 lakhs. I currently have an outstanding home loan of around 150 lakhs and since its at subsidised rate i plan to run it till retirement age 58. Me and my wife hold mediclaims of 20 lakhs plus 20 lakhs top.up and she has 50 lalkhs cover. We dont plan any kids. Is the allocation good for a happy and peaceful retirement or i should change some allocations?
Ans: You have already built a strong base at age 43. The Rs.46 lakh MF portfolio, Rs.50 lakh EPF, NPS, PPF and regular SIPs show good discipline. With around 15 years until age 58, you have a useful time period to improve the structure further.

» Your present position

Your financial assets are broadly spread across:

– Mutual funds: around Rs.46 lakh.

– EPF: around Rs.50 lakh.

– NPS: Rs.9,000 monthly.

– PPF: Rs.60,000–75,000 yearly.

– Gold: Rs.15,000 monthly.

– Home loan: around Rs.1.50 crore outstanding.

You also have health insurance and top-up protection. Since you do not plan to have children, your retirement planning can remain focused mainly on your own and your wife's future lifestyle and healthcare needs.

Overall, the foundation looks good. The main area for review is not your savings discipline. It is the asset allocation and concentration within your equity investments.

» Your mutual fund allocation

A Rs.46 lakh portfolio with around Rs.7 lakh in debt, money-market and arbitrage categories means a large part is in equity-oriented investments.

That can be suitable at age 43 if you have the ability to tolerate market falls and your retirement is around 15 years away.

But your equity allocation appears to have several market segments:

– Large-cap exposure.

– Large and mid-cap exposure.

– Small-cap exposure.

– Nifty 50 exposure.

– Next 50 exposure.

– Defence index exposure.

This needs some simplification.

You do not necessarily need many different categories to create diversification. Several of these can overlap in their underlying holdings.

» The defence index allocation needs attention

You mentioned a defence index allocation.

I would be careful about allowing a sector-specific allocation to become a major part of your retirement portfolio.

A sector can perform very strongly for a period and then go through a long period of weak performance.

For retirement planning, your core portfolio should not depend heavily on one sector.

A diversified actively managed equity allocation can spread the portfolio across different sectors and companies. The fund manager can also change the portfolio when business conditions change.

So, I would keep any sector-specific allocation as a small satellite portion rather than treating it as a core retirement investment.

» Your 15% annual increase is a good habit

Increasing your SIP every year is one of the strongest parts of your plan.

Your income may also increase over the coming years. If you can maintain a 10–15% annual increase without affecting your cash flow, it can materially improve your retirement corpus.

But there is one condition.

Do not increase equity SIPs blindly every year.

As you move towards age 53–55, gradually increase the safer portion of the retirement portfolio. The objective is not maximum equity exposure until age 58.

The objective is to reach retirement with a corpus that can withstand market volatility.

» Gold investment needs a separate review

Your Rs.15,000 monthly investment in gold through a jewellery chain needs clarification.

If this is jewellery purchase, I would not consider it equivalent to a financial investment.

Making charges, resale value and the purpose of the purchase can affect the outcome.

If the purpose is wealth diversification, financial gold instruments can be evaluated separately.

Also, you already have substantial exposure to financial assets. There is no need to keep increasing gold indefinitely.

A defined allocation is better than buying gold simply because it has performed well recently.

» EPF is an important retirement asset

Your Rs.50 lakh EPF balance is a major strength.

It gives your retirement portfolio a relatively stable component alongside equity investments.

Continue EPF as per your employment structure and applicable rules.

Since you have another 15 years, you do not need to shift the entire MF portfolio towards conservative assets today.

The better approach is gradual de-risking as retirement approaches.

» NPS and PPF

Your NPS contribution of Rs.9,000 per month adds another retirement-oriented asset.

Increasing it next year can be useful, provided your overall retirement allocation remains balanced.

Your PPF contribution is also useful as a conservative component.

You already have EPF + PPF + debt/money-market/arbitrage exposure. Therefore, there is no need to aggressively increase every debt component just for the sake of safety.

Your entire portfolio should be looked at together.

» The Rs.1.50 crore home loan

This is the biggest liability in your balance sheet.

Your decision to continue the loan because of the subsidised interest rate can be reasonable, provided the rate remains attractive and the EMI comfortably fits your cash flow.

But there is one important retirement point.

You plan to retire around age 58. Ideally, you should not enter retirement with a large outstanding home loan unless you have a very clear plan for servicing it.

You therefore have around 15 years to gradually reduce this liability.

Do not automatically stop all investments and prepay the loan today. Instead, compare:

– Effective home-loan cost.

– Expected long-term investment return.

– Tax benefits, if applicable.

– Your retirement corpus requirement.

– The outstanding loan expected at age 58.

This should be reviewed every few years.

» Your health insurance position

Your health cover appears reasonably structured from the information given.

You have:

– Rs.20 lakh base medical cover.

– Rs.20 lakh top-up.

– Additional cover for your wife.

However, retirement planning should not assume that today's insurance arrangement will remain sufficient forever.

Review the policies periodically for:

– Room-rent conditions.

– Co-payment.

– Waiting periods.

– Renewal terms.

– Restoration benefits.

– Top-up deductible.

– Coverage after retirement.

Healthcare expenses can become one of the largest retirement risks, so this part deserves regular review.

» Your retirement portfolio should change with age

At 43, you can still maintain meaningful equity exposure.

But I would broadly think of the journey in stages.

– Age 43–48: Continue growth-oriented investing while maintaining a meaningful debt allocation.

– Age 48–53: Start increasing the retirement safety bucket gradually.

– Age 53–58: Focus more on protecting the corpus already created and reduce dependence on equity market conditions.

– At retirement: Keep several years of expected expenses in relatively stable assets and use equity mainly for long-term inflation protection.

This gives you a better chance of handling a major market correction close to retirement.

» One important missing number

The most important number missing from your question is your expected retirement expense.

For a peaceful retirement, corpus size alone is not enough.

You should estimate:

– Present monthly household expenses.

– Expected expenses at age 58.

– Home-loan balance at age 58.

– Medical and insurance costs.

– Travel and lifestyle expenses.

– Expected income from EPF, NPS and other assets.

– Whether you want to leave a legacy or spend most of the corpus during your lifetime.

Without these numbers, nobody can confidently say that Rs.46 lakh + Rs.50 lakh + NPS + PPF is sufficient for retirement.

» A few changes I would consider

– Keep increasing SIPs annually as long as cash flow permits.

– Reduce unnecessary overlap between large-cap, Nifty 50 and other broad-market exposures.

– Keep small-cap exposure within a level you can tolerate during a major correction.

– Keep the defence allocation limited because it is sector-focused.

– Maintain a meaningful debt allocation and gradually increase it closer to retirement.

– Review whether jewellery purchases are actually serving an investment purpose.

– Track the expected home-loan balance at age 58.

– Review health insurance every year.

– Build a separate retirement corpus tracker covering MF + EPF + PPF + NPS + other financial assets.

» Tax planning during retirement

Tax should also be considered while creating the retirement withdrawal strategy.

For equity mutual funds, LTCG above Rs.1.25 lakh in a financial year is currently taxed at 12.5%, while STCG is taxed at 20%.

For debt mutual funds, taxation can depend on the applicable rules and your income-tax slab.

Therefore, the retirement withdrawal strategy should not simply be "withdraw X amount every month". Different assets can be used at different stages to manage both risk and taxation.

» Final Insights

You have built a good retirement foundation by age 43. The next stage is less about adding more and more products and more about improving the structure.

Your biggest areas to work on are:

– Simplify the equity portfolio.

– Control sector concentration.

– Continue the annual SIP increase.

– Maintain adequate debt allocation.

– Plan the home-loan position before age 58.

– Build a clear retirement expense target.

– Gradually reduce equity risk during the final 5–7 years.

With 15 years still available, there is enough time to strengthen the plan substantially. Your disciplined savings rate is a major positive. The focus now should be on making the portfolio simpler, balanced and retirement-ready.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 22, 2026
Money
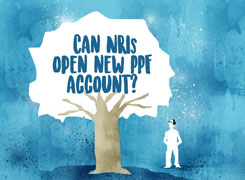
Dear Sir, My company got into NCLT 2 years ago and it is expected that we'll get our PF & VPF dues from EPFO in next month i.e. AUG'2026. I want to ask you where to put this amount of around 25 lacs, should I keep it parked with EPFO for another 3 years (I heard it would be tax-free in EPFO under my UAN for 3 years) or should I withdraw and put it in SWP (plz suggest top 3 swp scheme names) or should I keep it in some FD's. I'm presently doing a decent job overseas and donot need to withdraw it immediately for any another 3-4 years I hope. My son would be going to college in about 4-5 years so need to keep money aside for his college fees. I do have emergency funds for 8-10 months and i do have my insurance policies to cover for any untoward incidents. I need your help & guidance in planning, so if you have any other suggestion, plz do suggest. Also, advise me my tax liabilities on this amount. Thanks & regards, from AK Chaudhary
Ans: » Your Rs.25 lakh has three different jobs

You have provided the important details clearly. The fact that you already have 8–10 months of emergency funds and insurance is a strong starting point. Since your son needs the money in about 4–5 years, the Rs.25 lakh should be handled with both safety and growth in mind.

– Money required for your son's college in about 4–5 years.

– Money which may be required for other family needs.

– Money which can remain invested for 7–10 years or longer.

The first two portions should not be exposed to unnecessary equity risk. The third portion can have a higher growth component.

» First, a correction about keeping money in EPFO

I would not keep the Rs.25 lakh in EPFO merely because you heard that it will remain tax-free for three years.

There is no general rule that says EPF becomes tax-free simply because you keep it for another three years after leaving employment.

The tax treatment of your final PF withdrawal depends mainly on your total eligible service, the nature of the withdrawal and the applicable PF rules.

Therefore, do not make the investment decision based on the "3-year tax-free" information.

» Should you withdraw or leave it with EPFO?

If the Rs.25 lakh is genuinely credited to your EPFO account and you are eligible to retain it there, EPFO provides a relatively conservative retirement-oriented environment.

However, there is another important point.

You are presently working overseas and may have a different income-tax and residential status. Your Indian tax treatment can therefore depend on whether you are Resident, NRI or otherwise treated under the applicable rules.

Also, your PF service history matters.

If you have completed the required continuous service period, final PF withdrawal is generally treated much more favourably for tax purposes.

Therefore, before withdrawing, check your total PF service period and your residential status for the relevant financial year.

» I would not put the entire Rs.25 lakh into an SWP

This is an important point.

SWP is not an investment product.

SWP simply means withdrawing a fixed amount periodically from an existing mutual fund investment.

You first invest a lump sum in a suitable mutual fund portfolio and later withdraw a fixed amount through SWP.

If the underlying fund is equity-oriented, the value can fluctuate significantly. That can become uncomfortable when your son's college requirement is approaching.

So, I would not recommend taking Rs.25 lakh and immediately starting an SWP from an aggressive equity portfolio.

» What about FD?

FD can play an important role here.

Since your son's education requirement is around 4–5 years away, a portion of the money can be kept in bank deposits or other suitable fixed-income instruments.

This gives you:

– Better visibility of the money available.

– Lower market volatility.

– Easier planning for the education goal.

– No need to depend completely on equity market conditions when the college payment becomes due.

However, putting the entire Rs.25 lakh into FD may also reduce long-term growth potential, particularly if your actual requirement is 7–10 years away.

» A more balanced approach

Considering the information provided, I would think about the Rs.25 lakh in three buckets.

– Education bucket: Keep the amount expected to be required for your son's college relatively safe.

– Medium-term bucket: Invest in suitable fixed-income and conservative hybrid categories depending on your time horizon.

– Long-term growth bucket: If some money is not required for at least 7–10 years, a portion can be allocated to diversified actively managed equity mutual funds.

The exact allocation should depend on the expected college cost and your existing overseas savings.

» About the "top 3 SWP schemes"

I would not select three schemes merely because they are popular for SWP.

That approach can create another problem.

The correct question is:

"What portfolio should hold my Rs.25 lakh, and how much should I withdraw when required?"

Not:

"Which three schemes give the highest SWP?"

A suitable SWP portfolio should be selected based on risk, time horizon, asset allocation, taxation, liquidity and the amount required each year.

» Your overseas employment changes the planning

This is particularly important in your case.

Since you are working overseas, we need to know:

– Your present country of employment.

– Whether you are currently NRI under Indian tax rules.

– Whether the Rs.25 lakh will be credited to an existing EPF account.

– Your total PF service period in India.

– Whether you intend to return to India before your son's college education.

– Your existing investments in India and overseas.

These details can materially change the tax and investment decision.

» Tax treatment of the Rs.25 lakh

Do not assume that the entire Rs.25 lakh becomes taxable simply because you withdraw it.

The tax treatment depends on the nature of the PF withdrawal and your service history.

If the relevant conditions for tax-exempt PF withdrawal are satisfied, the accumulated PF amount can receive favourable tax treatment.

If your service period is below the required period, the position can be different. TDS and final income-tax liability are also not always the same thing.

Because your employer went through NCLT and the PF payment was delayed, I would also keep all PF statements, employer/NCLT records and EPFO correspondence safely. They may be useful if the source or period of the contribution needs to be established later.

» Do not forget the education goal

Your son's college is the most important factor in deciding the asset allocation.

Suppose the education requirement is due in only 4 years. You should not wait until the fourth year to shift the money from equity to safer investments.

The risk should gradually reduce as the goal approaches.

If the requirement is 5 years away, the strategy can be slightly different.

If some portion is needed only after 8–10 years, that portion can take more growth exposure.

» My overall assessment

I would not rush to withdraw the Rs.25 lakh just to start an SWP.

I would also not keep the entire amount in EPFO for three years based on the tax-free assumption.

A better approach is:

– First establish the exact tax treatment of your PF withdrawal.

– Confirm your Indian residential status.

– Confirm your total PF service period.

– Estimate your son's education requirement separately.

– Keep the near-term education requirement in safer assets.

– Use diversified actively managed equity mutual funds only for the portion having a sufficiently long horizon.

– Use SWP later as a withdrawal facility, not as an investment strategy.

Your existing emergency fund and insurance give you a good base. This Rs.25 lakh can then be planned specifically for your son's education and long-term family wealth, instead of treating the entire amount as one investment.

» Final Insights

Your situation does not require a choice between "EPFO or FD or SWP" for the entire Rs.25 lakh.

A combination can be much more suitable.

Most importantly, do not take an investment decision based on the belief that keeping the PF untouched for three years automatically makes the entire amount tax-free.

Since you are overseas and have a 4–5 year education goal, your residential status, PF service period and expected college requirement should be checked before the final allocation.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 22, 2026

Money
I have started a Mutual fund 2 years before and till now invested nearly 4 lakh, I invested in ICICI prudential business cycle fund , icici prudential manufacturing fund and SBI contra fund. The overall Absolute return of my portfolio is 1.52% and XIRR is 1.23%. Have I invested correct? When I ask my agent, they say that market has been down for last two years i should hold for next two year more atleast to see growth. This is the first time i invested in mutual fund, but i have lost trust. Am i stuck in wrong funds? Please advise.
Ans: You have started with a meaningful investment of nearly Rs.4 lakh, and the concern is understandable, especially when this is your first mutual fund experience. A low return after two years does not by itself mean that you selected wrong funds.

» What your current return tells you

– An absolute return of 1.52% and XIRR of 1.23% after around two years is certainly disappointing.

– However, judging an equity mutual fund portfolio only after two years can give a misleading picture.

– Equity investments can go through long periods of weak returns. The important question is not only what happened in the last two years, but whether the portfolio is suitable for your goal and investment horizon.

– So, I would not suggest exiting all your investments only because the current return is low.

» The bigger issue in your portfolio

Your three investments are not three completely different types of exposure.

– Business-cycle and manufacturing-oriented funds can have a strong sector or theme bias.

– A contra-oriented fund follows a different investment approach, but it is still an equity-oriented portfolio.

– Therefore, your Rs.4 lakh portfolio has meaningful dependence on particular investment styles and economic sectors.

This is more important than the fact that the return is currently low.

For a first-time mutual fund investor, I would generally prefer a well-diversified core portfolio rather than having a large portion concentrated in thematic or strategy-oriented categories.

» Should you hold for another two years?

Your agent is partly right that equity mutual funds should normally be given a longer horizon.

But simply saying "market was down, so wait two more years" is not enough.

The portfolio should be reviewed for:

– Your investment objective.

– Your total investment horizon.

– Your monthly SIP amount.

– Equity allocation required for your goals.

– Category diversification.

– Portfolio overlap.

– Risk level you can actually tolerate.

– Performance compared with the appropriate category and benchmark over a suitable period.

If these factors are satisfactory, continuing can make sense. If the portfolio structure itself is unsuitable, waiting another two years will not solve the underlying problem.

» Are you stuck in wrong funds?

I would not call them "wrong funds" merely because they have given low returns over two years.

The more relevant concern is whether they are the right categories for your overall financial plan.

A thematic or strategy-based fund can perform very differently from the broader equity market. Sometimes the theme works very well. Sometimes it can remain weak for a considerable period.

For a first-time investor, this can also create a psychological problem. When the portfolio does not perform, confidence falls quickly.

So, your loss of trust is understandable. But avoid making a second mistake by stopping equity investing completely because of a two-year experience.

» What I would do now

– Do not redeem everything immediately.

– Do not add fresh money blindly just because NAV has fallen or returns are low.

– Review the three holdings together as one portfolio.

– Identify how much of your total investment is concentrated in business-cycle and manufacturing themes.

– Build a stronger diversified core if your investment horizon is 7-10 years or more.

– Keep thematic exposure limited rather than allowing it to dominate the portfolio.

– Continue SIPs only after the overall asset allocation is reviewed.

– Keep money required within the next 3-5 years away from aggressive equity investments.

» Your first mutual fund experience

One important point here.

You have invested nearly Rs.4 lakh in two years. That is a good beginning towards creating long-term wealth.

Do not judge your entire mutual fund journey based on the first two years.

The real benefit of mutual funds comes from disciplined investing over a long period, proper diversification and staying aligned with your goals.

At the same time, "stay invested for the long term" should never become an excuse for not reviewing the portfolio.

A good investment professional should be able to explain why each category is being held, what role it has in your portfolio and what action should be taken if the investment does not perform as expected.

» What information is needed for a proper review

For a 360-degree assessment, I would need:

– Your age.

– Monthly income and monthly expenses.

– Current SIP amount in each fund.

– Present value of each investment.

– Your investment objective.

– When you need this money.

– Existing EPF, PPF, FD and other investments.

– Emergency fund availability.

– Insurance protection.

– Whether you have any loans.

With this information, the portfolio can be assessed as a complete financial plan rather than simply judging the present XIRR.

» Final Insights

Your current 1.23% XIRR is not a reason by itself to conclude that you are stuck in bad investments.

The bigger lesson is that your first portfolio appears to have meaningful thematic exposure. It deserves a proper category and asset-allocation review before you decide whether to continue, reduce or restructure.

Do not lose trust in mutual funds because of two weak years. But also do not continue blindly for two more years without understanding what you own and why you own it.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 18, 2026
Money
I am going to Retire in coming December 2026 ,thecorpus will be 2 crores with me. Kindly suggest how to maximize returns to get good returns because I don't have any other Income.
Ans: It is good that you have planned a Rs.2 crore retirement corpus before retiring. Since you will not have regular employment income after December 2026, the focus should not be only on maximising returns. Capital safety, regular income, inflation protection and liquidity are equally important.

» First Assess Your Retirement Requirement

Before investing the Rs.2 crore, identify:

– Your monthly household expenses after retirement
– Medical and healthcare requirements
– Any outstanding loans or liabilities
– Whether you have pension, rental income or any other income
– Financial support required for spouse or dependants
– Any major future expenses
– Expected retirement period, which could easily be 25–30 years or more

The most important question is not "How much return can I get?"

It is "How much can I withdraw without putting my retirement corpus at risk?"

» Do Not Put the Entire Rs.2 Crore in One Place

Since you have no other regular income, keeping the entire corpus in equity is risky.

Similarly, keeping the entire amount in bank deposits or other low-growth investments may create an inflation problem over a long retirement period.

A balanced structure can be considered:

– Keep a portion in safe and highly liquid investments for near-term expenses.
– Keep another portion in high-quality fixed-income investments for stability and regular cash flow.
– Keep a portion in diversified equity mutual funds for long-term growth and inflation protection.
– Maintain a separate medical and emergency reserve.

The exact allocation should depend on your age, monthly expenses and risk capacity.

» Use a Bucket Approach

A retirement corpus can be managed in different buckets.

– Short-term bucket: money required for the next few years. This should have low volatility and high liquidity.

– Income bucket: money meant to support regular withdrawals over the medium term.

– Growth bucket: money that can remain invested for many years and help the corpus fight inflation.

This structure is useful because you need not sell equity investments during every market fall to meet your monthly expenses.

» Be Careful With Monthly Withdrawals

A common mistake after retirement is to withdraw a fixed high amount without checking whether the corpus is growing or declining.

Your withdrawal should be reviewed every year based on:

– Actual expenses
– Inflation
– Portfolio performance
– Market conditions
– Remaining corpus
– Healthcare requirements

During strong market periods, you may have more flexibility. During weak market periods, controlling discretionary expenses can protect the corpus.

» Equity Is Still Important

Retirement does not mean that equity should become zero.

If you are expected to live for another 25–30 years, inflation can significantly reduce the purchasing power of your money.

A suitable portion of diversified, actively managed equity mutual funds can provide long-term growth potential. But this portion should be based on your ability to tolerate market fluctuations.

Do not invest the entire Rs.2 crore in equity just to maximise returns.

» Keep Healthcare Separately

Medical expenses can be one of the biggest retirement risks.

Ensure you have adequate health insurance and a separate medical reserve. Do not depend completely on your Rs.2 crore investment corpus for unexpected hospital expenses.

» Tax Planning Also Matters

Your post-retirement tax liability should be considered while selecting the mix of investments and planning withdrawals.

For equity mutual funds, LTCG above Rs.1.25 lakh is currently taxed at 12.5%, while STCG is taxed at 20%, subject to applicable rules.

Tax-efficient withdrawals can improve the amount actually available for your monthly expenses.

» Avoid Chasing High Returns

At retirement, taking excessive risk for higher returns can be harmful.

An investment promising very high returns usually comes with higher risk. Your priority should be sustainable retirement income, not the highest possible return in any single year.

A good retirement portfolio should give you:

– Regular cash flow
– Liquidity
– Capital stability
– Long-term growth
– Inflation protection
– Tax efficiency
– Emergency protection

» Final Insights

Rs.2 crore can provide a meaningful retirement base, but whether it is sufficient depends mainly on your monthly expenses and retirement period.

I would not recommend deciding the investment allocation merely from the corpus size. Your age, monthly expense, spouse requirements, health cover, pension or other income and desired legacy should all be considered together.

A proper 360-degree retirement plan can then decide how much should remain safe, how much can generate income and how much should remain invested for long-term growth.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 18, 2026
Asked by Anonymous - Sep 17, 2026
Money
38.5 year are still age for home laon if no any disease?
Ans: Yes. At 38.5 years, you are generally still within the acceptable age range for a home loan, especially if you have stable income and no major health issues.

Your age alone should not be a major problem.

» What Lenders Mainly Check

Banks and housing finance companies normally look at:

– Your monthly income and job stability
– Existing EMIs and other liabilities
– Credit score and repayment history
– Age and remaining working years
– Loan amount required
– Property value and legal documents
– Existing financial commitments

Good health is useful, but home loan approval is mainly based on your financial profile and repayment capacity.

» Loan Tenure Matters

At 38.5 years, you may still get a reasonably long tenure, depending on the lender and your retirement age.

However, a longer tenure means more total interest. So, do not select the maximum tenure only to reduce the monthly EMI.

A practical approach is to keep the EMI comfortable and use future salary increases or bonuses for planned prepayments.

» Check Your Overall Financial Position

Before taking the loan, look at the complete picture:

– Keep an emergency fund for at least 6 months of essential expenses.
– Maintain adequate term insurance covering the outstanding loan and family needs.
– Have sufficient health insurance.
– Continue your retirement investments even after starting the EMI.
– Avoid taking additional loans simply because your income permits it.
– Ensure the home EMI does not put excessive pressure on monthly cash flow.

» Final Insights

At 38.5 years, it is not too late to take a home loan. Your stable income, credit history and repayment capacity are more important than age alone.

If the property is for your own use and the EMI comfortably fits your long-term financial plan, age should not by itself stop you from considering the loan.

As an Investment professional , I would suggest assessing the home loan along with retirement, family protection, emergency fund and other financial goals. This gives you a proper 360-degree financial view.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 16, 2026
Asked by Anonymous - Sep 16, 2026
Money
I Am 37 yrs old, working in a product-based semiconductor company. Family with housewife and one daughter 9 yrs old. Current salary is 3.3L after deduction, take home is around 2.3L. One home and housing plot worth 1cr(EMIs completed). My liabilities are, One more house currently I am residing in (worth 1.4cr, loan 1cr, still 19years EMI left) car loan (28k per month for next 2.8yrs), Hand loan from brother (5L, paying only interest /1rupee). I have MF 21.5L, Indian shares 10L, US Shares 10L, SSY 6L, NPS 6.5L, PF 26L. Insurance 3.5cr personal term policy, 1cr term policy from company. Ancient properties ~1Cr. My future requirements are 6Cr for retirement carpus, 2cr for my kid higher studies and marriage. In next 13 yrs I want to make this corpus and retire at the age of 50. Please suggest. My salary breakdown Deduction before take home:- PF-21k+21K Corporate NPS-18K ESPP-23K Take home: -2.3L Home loan-81K Car loan-28K Personal loan:-5K Investments:- SSY:-4K MFs:-54K (Distributed to multi cap, small cap, multi-asset funds) Chitti:-13K Rental income: -27K (from my first house and the house in my native place) Annually I used to get 2-3L as performance bonus, that fund I use for insurance premium payments and my daughter school fee.
Ans: » First priority: separate your goals

Your two major goals are:

– Retirement at age 50: Rs.6 crore
– Daughter higher education and marriage: Rs.2 crore
– Total future requirement: Rs.8 crore

I would not treat Rs.8 crore as one single investment goal.

Your daughters education goal has a nearer time horizon. Retirement has a longer horizon. So both should have separate investment strategies.

Also, Rs.2 crore for education and marriage 13 years from now may need to be reviewed periodically because education costs can rise faster than normal inflation.

» Your present financial position

You already have approximately Rs.80 lakh in financial assets:

– Mutual funds: Rs.21.5 lakh
– Indian shares: Rs.10 lakh
– US shares: Rs.10 lakh
– SSY: Rs.6 lakh
– NPS: Rs.6.5 lakh
– PF: Rs.26 lakh

This is a good base.

You also have significant property assets, but I would not depend on property appreciation for your Rs.8 crore financial goals.

Your retirement planning should mainly depend on financial assets and regular savings.

» Your biggest strength is your monthly saving

Your current monthly allocations are quite substantial:

– PF: Rs.42,000 including employer contribution
– Corporate NPS: Rs.18,000
– ESPP: Rs.23,000
– Mutual funds: Rs.54,000
– SSY: Rs.4,000
– Chitti: Rs.13,000

So your overall wealth creation is much higher than the Rs.54,000 MF SIP alone.

This is an important point.

Do not judge your retirement plan only by looking at the MF SIP.

PF, NPS, ESPP and other investments also form part of your retirement wealth.

» Do not increase equity exposure blindly

You already have:

– Indian shares
– US shares
– Mutual funds
– ESPP
– PF
– NPS

There is a reasonable amount of diversification, but your ESPP creates an additional concentration risk if you continue accumulating a large amount of your employer company shares.

Your salary, career and ESPP are already connected to the same company.

So periodically review the overall exposure to your employer stock. Avoid allowing one company to become a very large portion of your total financial assets.

» Mutual fund portfolio

Your Rs.54,000 monthly MF investment is currently spread across multi-cap, small-cap and multi-asset categories.

The broad approach is reasonable, but the portfolio should be checked for overlap.

You do not need many funds simply for diversification.

For a 13-year retirement goal, the important factors are:

– Appropriate equity allocation
– Diversification across market segments
– Fund quality and consistency
– Avoiding excessive small-cap exposure
– Regular portfolio review
– Gradually reducing risk as age 50 approaches

Small-cap exposure can be useful for long-term wealth creation, but it should not become the main retirement allocation.

» Use your future cash-flow increases carefully

Your car loan of Rs.28,000 will finish in about 2.8 years.

This Rs.28,000 should not become lifestyle expenditure after the loan ends.

Redirect it towards your financial goals.

Similarly, whenever your salary increases, increase your investments rather than allowing the entire salary increase to be absorbed by expenses.

This can make a major difference over the next 13 years.

» Home loan needs special attention

Your second house has a value of around Rs.1.4 crore and the outstanding loan is around Rs.1 crore, with 19 years remaining.

This is one area that needs serious review.

You want to retire at 50, but the home loan could continue until around age 56.

That creates a mismatch.

Before retiring at 50, you should ideally have a clear plan for the outstanding home loan.

You can consider using future bonuses, salary increases and the car-loan amount after closure to accelerate repayment, depending on the interest rate and your investment returns.

Do not take a decision based only on investment return expectations. Your retirement at 50 should be debt-light.

» Brother loan and personal loan

The Rs.5 lakh hand loan should also be reviewed immediately.

If the Rs.1 mentioned means 1% monthly interest, the effective cost is significant. In that case, clearing this liability should get priority over increasing investments.

Your Rs.5,000 personal-loan EMI should also be tracked and closed as per its interest cost and remaining tenure.

The objective is simple:

By age 50, your regular income should not be supporting large EMIs.

» What to do with the annual bonus

You receive Rs.2–3 lakh annually.

Currently, you use this for insurance premiums and your daughters school fees.

That is perfectly fine if these expenses are already part of your annual budget.

However, do not treat the bonus as regular retirement funding.

If there is any surplus after these expenses, use it for:

– Debt reduction
– Daughter education corpus
– Retirement investments

This gives your plan an additional boost without putting pressure on your monthly cash flow.

» Daughter goal needs its own bucket

Your daughter is currently 9.

Her higher education may begin around age 17–19. Therefore, the education portion of the Rs.2 crore target has a much shorter horizon than your retirement goal.

Keep this money separate from your retirement corpus.

As the education date gets closer, gradually move the required amount towards relatively stable assets.

Do not keep the entire education corpus in aggressive equity until the actual requirement date.

Marriage planning can have a longer horizon and can therefore follow a different asset allocation.

» Retirement at age 50

Retiring at 50 is possible only if you build two things:

– Sufficient corpus
– Sufficient income from that corpus

The Rs.6 crore target should therefore not be treated as a magic number.

You should calculate your expected expenses at age 50 and then check whether Rs.6 crore can support those expenses for the rest of your life.

You may potentially live for 30–40 years after retirement.

So inflation and healthcare costs are very important.

Also, retirement at 50 means you cannot depend on normal employment income for another 10–15 years. Hence, the corpus needs to be stronger than what would be required for someone retiring at 60.

» Important retirement milestone: age 45

I would create an important checkpoint at age 45.

At 45, review:

– Actual retirement corpus
– Outstanding home loan
– Daughter education corpus
– Annual family expenses
– Health insurance
– Life insurance
– Emergency reserve
– Equity exposure
– Employer stock exposure

If the numbers are not moving towards the required level, age 50 retirement can be reconsidered before making the final decision.

There is no harm in targeting 50 and eventually deciding that 52 or 53 gives much better financial comfort.

» Insurance review

Your personal term insurance of Rs.3.5 crore is substantial.

The additional Rs.1 crore company term cover is useful while you remain employed, but it should not be counted as permanent family protection because employment can change.

The personal cover is therefore more important.

Check that the cover is sufficient until your major liabilities and daughters financial requirements are substantially addressed.

Also maintain adequate family health insurance. Your financial plan should not depend only on the employer medical cover.

» Emergency fund

With a Rs.81,000 home-loan EMI, Rs.28,000 car EMI and family responsibilities, maintain a proper emergency reserve.

I would target at least 9–12 months of essential family expenses and EMIs.

This is especially important because you work in a specialised semiconductor industry where a job change or employment gap can affect cash flow.

Keep the emergency reserve separate from equity investments.

» Property should not be the retirement solution

You already own substantial property.

That is useful for family security, but I would not add more property to achieve your Rs.8 crore target.

Your future surplus should mainly strengthen liquid financial assets and retirement investments.

The first house is already generating rental income of Rs.27,000, which is useful cash flow.

» A simple priority order

For the next few years, I would follow this sequence:

– Maintain adequate emergency reserve.

– Continue disciplined retirement and goal investments.

– Review and reduce expensive debt.

– Do not allow employer shares to become excessive.

– Keep daughters education corpus separately identifiable.

– When the car loan ends, redirect the full Rs.28,000 towards your goals.

– Increase investments whenever salary increases.

– Use surplus annual bonus for debt reduction or goal funding.

– Around age 45, start reducing the risk of money required for near-term education.

– Around age 47–48, seriously work towards becoming debt-free before retirement.

» Final Insights

Your financial position at age 37 is encouraging.

The biggest positive is that you already have around Rs.80 lakh in financial assets and are directing a substantial amount of your income towards wealth creation.

The biggest challenge is not your present corpus. It is the combination of:

– Rs.8 crore total goal
– Retirement at only 50
– Rs.1 crore home loan
– Daughter education and marriage
– Long post-retirement period

So I would not suggest simply increasing your Rs.54,000 MF SIP and assuming everything will work out.

Your entire cash flow needs to be planned.

The most important move is to make sure every salary increase and every loan closure increases your long-term investment capacity.

With disciplined investing, controlled liabilities and periodic goal reviews, you have a reasonable opportunity to build a substantial corpus over the next 13 years. The exact retirement date should finally be decided based on the corpus and your actual expenses at that time, not age 50 alone.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 16, 2026

Money
I am retired at the age of 57 years. I have withdrawn 25% of EPF amount as advance after one year of retirement, I am planning to withdraw balance 95% of EPF amount after completion of 3 years, ie at the age of 60. How the Income Tax will be calculated on the acumulated Intrest amount post retirement after 57 year, while withdrawing final EPF
Ans: » EPF tax treatment after retirement

Your question is important because EPF treatment after retirement can be slightly different from normal EPF withdrawal rules.

The key point is that retirement at age 57 and withdrawal at age 60 does not automatically make the entire EPF interest taxable.

» Tax treatment of EPF withdrawal

If your EPF withdrawal qualifies as an exempt withdrawal under the applicable provident fund rules, the accumulated EPF balance, including eligible interest, is generally not taxed merely because you withdraw it after retirement.

Therefore, the fact that you leave the EPF balance for three years after retirement does not, by itself, mean that the entire interest earned during those three years becomes taxable.

» Interest earned after retirement

This is the important part of your question.

After retirement, you are no longer making fresh employee contributions. EPFO may continue to credit interest on the balance for the period for which the account remains eligible for interest.

The tax treatment depends on the nature of the interest and the applicable provident fund rules.

– Interest relating to the normal eligible EPF balance can continue to enjoy the applicable tax exemption.

– Interest relating to a taxable contribution account, such as interest arising from contributions above the prescribed tax-exempt contribution limits, can be taxable.

– Therefore, you should not assume that all interest credited between age 57 and 60 will automatically be added to your taxable income.

» Your 25% advance withdrawal

The 25% EPF amount you have already withdrawn is also relevant.

An EPF advance is different from final settlement. You should retain your EPFO statement showing:

– Balance before the advance

– Amount withdrawn as advance

– Interest credited subsequently

– Balance remaining in the account

– Taxable and non-taxable portions, if separately shown

This will make the position much clearer when you finally settle the account at age 60.

» Withdrawal at age 60

At age 60, you will be treated as a senior citizen for income-tax purposes, subject to the applicable residential status and tax rules.

However, becoming a senior citizen does not itself change an otherwise exempt EPF withdrawal into taxable income.

Your other income during that financial year will still matter for your overall income-tax position.

» One important point to verify

Since you retired at 57 and intend to keep the EPF balance until 60, I suggest obtaining your latest EPFO member passbook or statement before final withdrawal.

Check specifically whether the interest credited after retirement is shown as:

– Non-taxable EPF interest, or

– Taxable interest, if any.

This is much safer than assuming that the entire post-retirement interest is taxable.

» 360-degree retirement view

Since you are already retired, the bigger question is not only the tax on EPF interest.

You should also review:

– How much EPF should be withdrawn at 60

– Your monthly retirement-income requirement

– Pension income, if any

– Bank FD and other fixed-income income

– Income-tax liability after retirement

– Emergency reserve

– Medical and health-insurance requirements

– How the remaining retirement corpus should be invested for 20–30 years

At age 60, preserving purchasing power becomes very important. Keeping the entire retirement corpus only in low-return products may create an inflation risk over a long retirement period.

» Final Insights

In your situation, the entire interest accumulated from age 57 to 60 should not automatically be treated as taxable merely because you retired at 57.

The exact treatment depends on the nature of your EPF balance and whether any portion falls under the taxable contribution and interest rules.

Before making the final withdrawal, obtain the latest EPFO statement and check the taxable and non-taxable components. This can help you avoid unnecessary tax or incorrect reporting.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 15, 2026
Asked by Anonymous - Sep 14, 2026
Money
It's been 15 days since I have posted a question and still no answers. This is really pathetic. If you cant respond a basic question in a week or two then the same should be mentioned. Its really unprofessional and dissatisfying service provide by Redid gurus. Reposting for your reference, Hi expert, In 2010, I made a one-time lump-sum investment of approximately 50000k each in the following 13 funds. I have not added fresh capital to these funds since 2010: DSP-BR India TIGER Fund – Regular Plan - IDCW DSP-BR Top 100 Equity Fund – Regular Plan - IDCW Franklin India Flexi Cap Fund – Regular Plan - IDCW HSBC Large Cap Fund – Regular Plan - IDCW (Formerly L&T India Large Cap Fund / HSBC Advantage India Fund) HSBC Progressive Themes Fund – Regular Plan - IDCW Nippon India Growth Fund – Regular Plan - IDCW Nippon India Power & Infra Fund – Regular Plan - IDCW SBI Magnum Midcap Fund – Regular Plan - IDCW SBI Contra Fund – Regular Plan - IDCW (Formerly SBI Magnum Sector Funds Umbrella Contra) Sundaram Large Cap Fund – Regular Plan - IDCW Sundaram Diversified Equity Fund – Regular Plan - IDCW HDFC Infrastructure Fund – Regular Plan - IDCW Edelweiss Mid Cap Fund – Regular Plan - IDCW (Payout) Part from the above active monthly SIPs (Current Portfolio – ₹40,000/month total) I am currently investing ₹10,000 per month in each of the following 4 funds: HDFC Children's Gift Fund – Regular Plan (Growth) (Includes lock-in) Mirae Asset Large & Midcap Fund – Regular Plan (Growth) (Formerly Mirae Asset Emerging Bluechip Fund) Parag Parikh Flexi Cap Fund – Regular Plan (Growth) HDFC Multi Cap Fund – Regular Plan (Growth). Considering my current valuation in the legacy 2010 funds alongside my 40,000 monthly SIPs, what is a realistic, risk-adjusted corpus projection for 2035 (10 years) and 2040 (15 years) assuming standard equity growth rates? Also the one time payments I made should I leave those funds or reallocate? Basically which are the food funds and which arent.
Ans: You have actually done the difficult part well — you started investing early and continued your SIPs. The main issue now is not whether to invest more, but whether 13 old holdings are still needed in the portfolio.

» One correction in the old investment amount

You mentioned approximately “Rs.50,000k each”. I assume you mean around Rs.50,000 each.

If so, the original investment across 13 funds was roughly Rs.6.5 lakh. Since these investments are from 2010, the present value could be substantially higher, but the current valuation is essential before giving a proper corpus estimate.

» What I see in the legacy portfolio

The 13 old funds have a lot of overlap.

You have exposure to:

– Large-cap equity
– Mid-cap equity
– Flexi-cap/diversified equity
– Contra/value-oriented equity
– Infrastructure and thematic funds
– Sector-oriented funds

The biggest concern is not that all these funds are bad.

The concern is having too many funds doing similar jobs.

Some of these old funds may still be good investments. But a fund that was suitable in 2010 does not automatically remain the best choice in 2026.

» What should be retained

I would broadly divide the legacy holdings into three groups.

First, diversified equity categories.

– These can continue if their long-term performance, portfolio quality and fund-management consistency remain good.

Second, thematic/sector funds.

– These need more caution.

– Infrastructure, power and theme-based funds can perform very well during favourable cycles.

– But they can also go through long periods of underperformance.

– They should not form a major part of a core retirement portfolio.

Third, overlapping large-cap funds.

– Holding several large-cap funds does not necessarily give better diversification.

– There is usually considerable overlap in the underlying companies.

Therefore, the portfolio can be simplified without reducing its equity exposure.

» Your current Rs.40,000 SIP

This is actually the stronger part of your present strategy.

You are putting Rs.10,000 each into four different equity categories.

The broad structure gives you exposure to:

– Children's long-term goal
– Large and mid-sized companies
– Flexible diversified equity
– Multi-cap equity

This is much cleaner than maintaining 13 old funds.

However, even here, I would review the overlap between the diversified categories.

More funds does not mean more diversification.

» Should you immediately sell the 2010 investments?

No.

I would not recommend selling all the old investments just because they are old.

There are three things to check first:

– Current value of each fund
– Capital gains and tax impact
– Whether each fund still has a clear role in your portfolio

Since your investments are from 2010, many of them may have substantial accumulated gains.

A wholesale switch could create an unnecessary tax liability.

Also, do not judge a fund only by its current return.

Fund consistency, downside protection, portfolio quality, category performance and fund-management changes also matter.

» What I would do with the old funds

My preference would be consolidation rather than complete disruption.

– Stop fresh investment into weak or unnecessary categories.

– Retain the better diversified holdings where they still fit your asset allocation.

– Gradually exit excessive thematic/sector exposure.

– Consolidate overlapping funds.

– Redirect future SIPs towards a smaller number of well-selected categories.

This can make the portfolio much easier to monitor.

You dont need 17 funds to build a strong long-term portfolio.

» 2035 corpus expectation

There is one important limitation.

You have not provided the current market value of each of the 13 legacy investments.

Therefore, a precise projection would be misleading.

Your Rs.40,000 monthly SIP alone can become a meaningful corpus over the next 10 years if equity markets deliver reasonable long-term returns.

The existing 2010 corpus will be an additional and potentially significant contributor.

So your 2035 corpus should be assessed using:

– Current value of all legacy investments
– Rs.40,000 monthly SIP
– Any future SIP increases
– Reasonable equity return assumptions
– Tax and costs at the time of withdrawals

I would use a range rather than promise a single number.

» 2040 corpus expectation

The 15-year horizon is even more favourable for equity investing.

Compounding becomes much more powerful over this period.

If you maintain Rs.40,000 monthly SIPs and increase them gradually with your income, your eventual corpus can be considerably higher than what a flat Rs.40,000 SIP would produce.

This is where your strategy can become really powerful.

The most important factor is not finding the perfect fund.

It is maintaining a disciplined investment rate for the next 10–15 years.

» IDCW option needs review

Almost all your old investments are in IDCW options.

For long-term wealth creation, IDCW is generally not my preferred structure.

IDCW payouts are not extra returns. The NAV gets adjusted when a distribution is made.

If you do not need periodic cash from these investments, the growth option is generally more suitable for a long-term accumulation objective.

But do not switch blindly.

First check the current value, accumulated gains and tax impact.

» A better portfolio structure

Instead of maintaining 13 legacy funds plus 4 SIP funds, I would aim for a simpler structure.

– Core diversified equity allocation

– Large and mid-cap exposure

– Multi-cap/flexi-cap exposure

– Limited mid-cap exposure where suitable

– Limited thematic exposure, only if there is a clear reason

– Separate debt/PPF/FD allocation for stability and near-term goals

This gives you a much clearer portfolio.

» One more important point

Your Children's Fund has a lock-in.

Therefore, that investment should be linked specifically to the child's goal and the required year of money.

As the goal approaches, gradually reducing equity exposure becomes important.

Do not remain 100% equity just because the investment has performed well historically.

» My overall assessment

Your investing discipline since 2010 is a big positive.

The portfolio does not look like something that needs to be completely thrown away.

It needs cleaning.

I would rate the situation like this:

– Long-term investing discipline: Strong
– Equity exposure: Good
– Number of funds: Too many
– Category overlap: High
– Thematic exposure: Needs review
– IDCW usage: Needs review
– Current SIP structure: Reasonably well organised
– Need for consolidation: High

The next step should be a fund-by-fund assessment of the 13 legacy holdings, but without looking only at past returns.

If you provide the current value of each of those 13 investments, I can classify them into “Continue”, “Hold but gradually consolidate” and “Consider exiting”, while also assessing the likely 2035 and 2040 corpus more meaningfully.

» Final Insights

You do not have a bad portfolio.

You have an old portfolio that has accumulated too many moving parts over 16 years.

That is actually a much easier problem to solve.

I would avoid unnecessary churning, protect the benefit of your old investments, control taxation, simplify overlapping holdings and continue the Rs.40,000 SIP with periodic increases.

With a 10–15 year horizon, disciplined investing and a cleaner portfolio, you have a good opportunity to build a substantial corpus.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188
www.holisticinvestment.in
https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 15, 2026

Asked by Anonymous - Sep 14, 2026
Money
Hi I'm 34 yo working female. Employed in central government earning 51k pm inhand. I hv around 8L in mf, 1.4L in stocks, 3L in ppf, 4.7L in fds n rd...I have another 4L liquid cash available for investment, which I want to use to generate monthly income without locking in, so that it's accessible incase of emergency What are my options?
Ans: You have built a good base already, with MF, PPF, FDs/RD, stocks and liquid cash. The key is to separate emergency money from money meant for monthly income.

» First priority – emergency fund

Since you are a central government employee with regular income, your job gives you some stability. Still, keep a proper emergency reserve.

– From the Rs.4 lakh available, I would first keep around 3–6 months of essential expenses in a highly liquid bank deposit/savings arrangement.

– This portion is not for generating returns. Its job is to be available immediately when required.

– Your existing FDs/RD can also form part of the emergency reserve, depending on their maturity and withdrawal conditions.

» For monthly income without a lock-in

For the remaining amount, a short-duration debt-oriented mutual fund can be considered.

– It can provide better flexibility than putting the entire amount into a long-term FD.

– You can use a systematic withdrawal facility when you actually need regular cash flow.

– There is no fixed monthly income guarantee. The withdrawal should be planned based on your requirement and the portfolio value.

– Debt funds can also have some market-related movement, so they are not the same as a bank FD.

Another option is a sweep-in/sweep-out FD or a suitable short-term bank deposit.

– This gives easy access to money.

– Returns are generally more predictable than debt funds.

– However, the interest may not be as attractive as some other options, and premature withdrawal conditions need to be checked.

» Do not chase high monthly income

This is important.

Rs.4 lakh cannot safely generate a large monthly income while also preserving the capital forever.

If someone promises a high fixed monthly return with easy liquidity, be careful.

Your main objective should be:

– Capital safety
– Easy access during emergencies
– Reasonable return
– Tax efficiency
– Gradual wealth creation

» Your overall portfolio needs some structure

You currently have approximately Rs.17 lakh across MF, stocks, PPF, FDs/RD and the additional liquid cash.

Your portfolio is already reasonably diversified.

But I would not put the entire Rs.4 lakh into an income-producing investment.

A better approach may be:

– Keep an emergency reserve separately.

– Use only the surplus portion for monthly income.

– Continue long-term MF investments for wealth creation.

– Keep PPF as a long-term debt component.

– Avoid increasing direct stock exposure unless you have the time and knowledge to monitor it.

» One important point about monthly withdrawals

If your actual need is only occasional access to money, do not create a compulsory monthly withdrawal.

Instead, keep the money invested and withdraw only when required.

This gives your corpus more opportunity to grow.

If you genuinely need a fixed monthly amount, then a planned withdrawal strategy can be considered after checking your expenses, existing SIPs and future goals.

» 360-degree view

At age 34, your biggest advantage is time.

Your Rs.8 lakh MF portfolio can potentially become a much larger retirement corpus if you continue investing for the next 20–25 years.

So I would not convert a large part of your portfolio into an income-focused portfolio at this stage.

Your monthly salary should ideally fund your regular expenses, while investments should primarily build wealth.

The Rs.4 lakh should therefore be treated as a liquidity decision, not just a return decision.

» Final Insights

You are in a good starting position. The next step is to clearly divide your money into emergency fund, short-term needs and long-term wealth creation.

For the Rs.4 lakh, keep the emergency portion immediately accessible. The balance can be considered for a suitable short-duration debt option or flexible deposit, based on your risk level and tax position.

For a more precise 360-degree plan, your monthly household expenses, existing MF SIP amount, dependants, insurance cover and major goals such as house, marriage or retirement would be important.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188
www.holisticinvestment.in
https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 13, 2026
Asked by Anonymous - Sep 11, 2026
Money
I am a 25 yo looking to fix my money problems. Plsssss help!!!!!!!
Ans: At 25, you have something very valuable: plenty of time to correct money mistakes.

You do not need a perfect investment plan today. You need a simple system that you can follow every month.

» Step 1: Know Where Your Money Goes

For the next 2–3 months, track every rupee coming in and going out.

Separate expenses into:

– Essential expenses
– Family commitments
– Lifestyle spending
– EMIs and other debts
– Savings and investments

This will show where your money problem actually is.

» Step 2: Clear Costly Debt First

If you have credit-card outstanding, personal loans or other high-cost debt, give priority to clearing them.

Do not take more investment risk while expensive debt is eating into your income.

» Step 3: Build An Emergency Fund

Before increasing mutual fund investments, create an emergency reserve.

Keep around 4–6 months of essential expenses in easily accessible, safe options.

This money is not for wealth creation. It is for emergencies such as job loss, family needs or sudden expenses.

» Step 4: Start Investing Systematically

After your emergency fund and debt are under control, start a monthly SIP.

A diversified equity mutual fund portfolio can be considered for goals that are at least 7–10 years away.

Do not select funds simply because they gave high returns recently.

The investment should match your goal, time period and ability to handle market ups and downs.

» Step 5: Increase Savings With Income

At 25, your income may grow considerably over the next 10 years.

Whenever your salary increases:

– Increase your SIP.
– Avoid increasing lifestyle expenses at the same speed.
– Keep bonuses partly for financial goals.
– Build separate funds for short-term and long-term goals.

This can make a much bigger difference than trying to find the highest-return investment.

» Step 6: Protect Yourself

A 360-degree money plan also needs protection.

– Maintain adequate health insurance.
– If you have financial dependants, consider suitable term insurance.
– Keep nominees updated on your financial accounts.
– Avoid mixing insurance and investment without understanding the costs and benefits.

» Step 7: Keep Goals Separate

Create separate buckets for:

– Emergency money
– Short-term goals within 3 years
– Medium-term goals of 3–7 years
– Long-term wealth creation

Money needed soon should not be exposed heavily to equity market risk.

» Finally

At 25, even if your finances currently feel messy, you are very far from being financially stuck.

Start with three things: control expenses, remove costly debt and build an emergency fund. Then increase your long-term investments gradually.

If you share your monthly income, expenses, existing loans, savings, investments and major goals, an Investment professional can assess the complete picture and suggest a more suitable 360-degree structure.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 13, 2026
Asked by Anonymous - Sep 13, 2026
Money
Hello sir, I am a mbbs second year student (about to finish) and currently earn about 50K from a part time job. After house expenses my savings are around 20K. I have recently invested in following sip- Parag Parikh direct growth 2.5K monthly ; hdfc large and mid cap 2.5K monthly ; hdfc defense 1K monthly I wish to grow this money in 5 years to somewhat amount to afford a down payment for a house on home loan as soon as I start my pg Any suggestions about my current sip and where should I put rest of my money?
Ans: It is good that you have started investing while still in your second year of MBBS. Building the saving habit at this stage can give you a strong financial base when your medical career grows.

You currently save around Rs.20,000 every month. Your present SIP is Rs.6,000, leaving around Rs.14,000 for other financial priorities.

» Your 5-Year House Goal

A 5-year period is relatively short for an equity-heavy portfolio, especially when the money is specifically required for a house down payment.

Your PG admission and career transition may also bring large expenses. So, the house fund should not depend entirely on equity market returns.

I would suggest keeping the house down-payment goal separate from your long-term wealth creation.

– Money required within 5 years: moderate-risk investments with increasing debt allocation as the goal approaches.

– Money required after 10 years: equity-oriented mutual funds can have a larger role.

» Review of Your Existing SIPs

Your portfolio has three different exposures:

– A diversified equity fund gives broad exposure and can remain a core long-term holding.

– A large and mid-cap fund can also be useful for long-term wealth creation.

– A defence-sector fund is a thematic investment. It can be more volatile because its performance depends heavily on one sector.

For a 5-year house goal, I would not make the thematic fund a major part of your savings. You may consider keeping the exposure limited and directing fresh money towards diversified investments.

» Direct Plan Vs Regular Plan

You are currently using direct mutual fund plans. Direct plans have a lower expense ratio because there is no distributor commission.

However, for a young investor starting his financial journey, the service and review support available through an MFD can be valuable.

A regular plan through an AMFI-registered MFD can provide:

– Portfolio review and rebalancing support.

– Help in matching investments with your changing goals.

– Guidance when markets fall sharply.

– Assistance with nominations, transactions and documentation.

– Review when your income changes substantially after MBBS and during PG.

The cost difference should therefore be evaluated along with the service you actually receive. If you are comfortable selecting, monitoring and reviewing everything yourself, direct plans can be suitable. Otherwise, regular plans through an MFD can offer useful ongoing support.

» Where To Put The Remaining Rs.14,000

I would not immediately put the entire balance into equity SIPs.

Your first priority should be an emergency reserve. Since you are studying and working part-time, your income may change during PG.

You can divide the remaining savings broadly into:

– Rs.8,000–Rs.10,000 towards a safe house/PG reserve.

– Rs.4,000–Rs.6,000 towards additional long-term wealth creation.

The safe portion can be built through suitable bank deposits or high-quality short-duration debt-oriented investments, depending on your exact need and tax position.

» Do Not Take A Large Home Loan Too Early

This is especially important in your case.

Your income may rise significantly after PG, but your education and career path can also involve relocation, fees and other expenses.

Buying a house immediately after starting PG may therefore put unnecessary pressure on your cash flow.

It may be better to first build:

– Emergency fund.

– PG education fund.

– House down-payment fund.

– Adequate health insurance.

– Personal term insurance when you have financial dependants.

Then decide the home-loan amount based on your stable post-PG income.

» A Better 360-Degree Approach

Your present age gives you a major advantage: time.

Do not focus only on maximising the SIP return. Focus on building financial flexibility.

For the next few years:

– Continue disciplined monthly investing.

– Keep the house corpus separate from retirement/long-term wealth.

– Reduce dependence on the thematic fund.

– Build an emergency reserve.

– Avoid unnecessary loans and lifestyle commitments.

– Increase SIPs whenever your income rises.

Once you complete PG and your income becomes stable, you can substantially increase your equity SIP and build wealth much faster.

» Final Insights

Your starting point is quite strong for an MBBS student. The important thing now is not to chase very high returns.

Your 5-year house goal needs capital protection as the date comes closer. Your long-term wealth goal can take more equity risk.

With disciplined saving now and a meaningful SIP increase after PG, you can create a much stronger financial position before taking a home loan.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 12, 2026
Money
Sir, I have a lic jeevan suraksha poliy plan 122 - 27 Yrs with terminal Bonus, Without Life Cover, Policy Issue date 1.7.2001, VEsting Date 30.3.2028, yearly Premium Rs 9918/-Monthly Annuity Rs 9990/- - NCO - Rs 1200000/- . I wanted to now if LIC actually declares any SRB in addition to NCO for policy. and If yes, What would be the Approximate Corups available to me on the vesting date for me to choose between the Options
Ans: You have given the important policy details, and the vesting date is quite close. This is a useful time to review the available options carefully.

Your policy appears to be the old deferred annuity plan, Plan 122, issued in 2001. The plan provides for a deferred annuity and includes provision for a terminal bonus.

» Will you get SRB in addition to Rs. 12 lakh NCO?

The important point is that the benefit in your policy should not be assumed to be a normal Simple Reversionary Bonus (SRB), like in a traditional participating endowment policy.

For this particular plan, the benefit structure refers to a Final Additional Bonus / Terminal Bonus payable at vesting, subject to LICs declaration and the terms applicable to your policy.

Therefore:

– Your Rs. 12 lakh NCO is the important base figure.

– A terminal/final additional bonus may be payable in addition to this amount.

– The bonus cannot be safely estimated merely by applying the current LIC bonus rates.

– The final amount will depend on the bonus actually declared by LIC for your particular policy at vesting.

So, I would not advise you to assume a particular bonus amount before LIC confirms it.

» Approximate corpus at vesting

Since your vesting date is 30.03.2028, there is still some time left.

For planning purposes, I would treat Rs. 12 lakh as the presently known NCO and consider the terminal bonus as an additional amount, rather than building your retirement decision around an assumed bonus.

A reasonable planning approach is:

– Base amount: Rs. 12 lakh NCO.

– Plus: terminal/final additional bonus, if declared and applicable.

– Final vesting value: to be confirmed by LIC before you exercise the annuity option.

I would be cautious about giving you a speculative corpus figure. It may look useful today, but it can create the wrong expectation.

» One important point about your Rs. 9,990 monthly annuity

You have mentioned:

– NCO: Rs. 12 lakh

– Monthly annuity: Rs. 9,990

– Annual premium: Rs. 9,918

– Policy term: 27 years

– Vesting: 30.03.2028

At vesting, you should obtain a written quotation from LIC showing the NCO after applicable bonus and the annuity payable under each available option.

The choice exercised at vesting is important because it determines your future pension structure and other benefits.

» What I suggest you do before 30.03.2028

About 6–12 months before vesting, ask LIC for a written statement showing:

– Present NCO.

– Terminal/final additional bonus credited or payable.

– Final amount available at vesting.

– Monthly annuity under each available option.

– Whether any commutation option is available to you.

– Death-benefit provisions under each option.

– Whether the Rs. 9,990 monthly annuity mentioned in your policy document remains applicable.

This is much safer than relying on an old policy document or verbal information.

» 360-degree retirement assessment

The bigger question is not only whether the corpus becomes Rs. 12 lakh or somewhat higher.

You should compare:

– The final LIC vesting amount.

– Pension available under each option.

– Whether you need regular income after 2028.

– Whether preserving capital for your family is important.

– Your other retirement assets and monthly income.

– Tax treatment of the income, where applicable.

– Liquidity required for medical and other emergencies.

Since this is an old policy and you have already paid premiums for many years, I would not suggest surrendering it at this stage without first checking the exact vesting benefits.

» Final Insights

Yes, your policy may have a terminal/final additional bonus in addition to the NCO, but I would not treat it as a guaranteed SRB or assume a fixed bonus amount.

For your decision-making, Rs. 12 lakh should presently be treated as the known base. The additional terminal bonus should be confirmed by LIC closer to the vesting date.

Most importantly, please obtain the official vesting quotation from LIC before choosing the annuity option. Once you have that quotation, the different options can be compared properly from an income, liquidity and family-benefit perspective.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 11, 2026

Money
I AM AGED ABOUT 56 AND HAVING A MEDICLAIM POLICY COVERING RS. 8.00 (EIGHT LAC) FOR ME AND MY SPOUSE WITH ORIENTAL INSURANCE COMPANY FROM LAST 10 YEARS, SOME ONE SUGGESTING ME FOR TOP UP PLAN FOR THE ABOVE POLICY, WILL IT BE HELPFUL. PLEASE ADVICE.
Ans: » Your Existing Health Cover

Maintaining the same mediclaim policy for around 10 years is a strong positive. Continuity can be very useful, especially as you are now 56.

Your present Rs. 8 lakh family cover may be adequate for smaller hospital expenses, but it may not be sufficient for a major hospitalisation in future.

So, considering your age, adding extra health cover is worth evaluating.

» Is a Top-up Helpful?

Yes. A top-up can be a cost-effective way to increase your overall health protection.

A top-up generally works after a specified deductible is crossed. For example, if the deductible is Rs. 8 lakh, the top-up starts paying only after eligible medical expenses cross that level.

Hence, your existing policy and the top-up can work together.

However, please do not select a top-up only because the premium is low.

» Top-up vs Super Top-up

This is an important point.

A normal top-up usually considers the deductible for each claim separately.

A super top-up generally considers the deductible based on total eligible medical expenses during the policy period.

For a family, a super top-up can often provide better practical protection.

Example: Suppose there are two hospitalisations in one year. The first costs Rs. 6 lakh and the second Rs. 5 lakh. A super top-up may consider the total eligible expenses, subject to its policy conditions.

So, compare both structures carefully.

» Do Not Disturb Your Existing Policy

Since you have maintained the existing policy for about 10 years, I would generally not suggest replacing it merely to get a larger cover.

Your existing policy may have valuable continuity benefits and accumulated waiting-period advantages.

First explore increasing protection through an additional top-up or super top-up.

» Important Conditions to Check

Before buying the additional cover, check these points carefully:

– Whether the deductible is individual or family based.

– Whether the deductible applies per claim or annually.

– Waiting periods for pre-existing diseases.

– Room-rent restrictions.

– Co-payment conditions.

– Disease-wise sub-limits.

– Coverage for daycare procedures.

– Cashless hospital network in your city.

– Restoration or refill benefits.

– Whether both you and your spouse are covered under the additional policy.

– Maximum entry age and renewal conditions.

– Whether the additional policy has its own waiting periods.

These conditions can matter more than a small difference in premium.

» Suggested Structure

At age 56, I would prefer a layered health-insurance structure rather than depending only on Rs. 8 lakh.

You can consider:

– Continue your existing Rs. 8 lakh policy.

– Add a suitable super top-up with a meaningful additional cover.

– Keep a separate emergency medical reserve for expenses not fully covered by insurance.

– Review the total family health protection every 2-3 years.

The exact additional cover should depend on your city, spouse age, health history, existing policy terms and premium affordability.

» Final Insights

Your existing 10-year policy is valuable. So, do not surrender or discontinue it without a proper comparison.

Adding a top-up can definitely strengthen your protection. However, I would specifically compare a super top-up also before taking the decision.

At 56, increasing health insurance protection now can give you much better peace of mind for the coming years. The earlier you arrange adequate cover, the better, because health insurance becomes more important as age increases.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Samraat

Samraat Jadhav  |2601 Answers  |Ask -

Stock Market Expert - Answered on Sep 10, 2026

Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 10, 2026

Money
I wanty to invest approx. 5 lakhs in different mutual funds which will give me average XIRR of 12 to 15%. Please csuggest me name and scheme of MF
Ans: Rs.5 lakh is a good starting amount. However, 12–15% XIRR should be treated as a long-term target, not a guaranteed return.

» Suitable fund categories

For a 5+ year horizon, I would consider a diversified active-fund portfolio such as:

Multi Cap Fund – 30%
Flexi Cap Fund – 25%
Large & Mid Cap Fund – 25%
Mid Cap Fund – 20%

This gives exposure to different company sizes and investment styles.

» If you want a simpler portfolio

You do not need 4–5 funds just because you have Rs.5 lakh.

A 3-fund structure can be sufficient:

Flexi Cap Fund – 40%
Large & Mid Cap Fund – 30%
Multi Cap or Mid Cap Fund – 30%

The actual scheme selection should depend on your time horizon, risk level and existing investments.

» About the 12–15% XIRR target

For equity mutual funds, 12–15% can be a reasonable long-term planning assumption over 7–10+ years.

But no mutual fund can promise this XIRR.

Short-term returns can be negative.
Even good funds can underperform for some periods.
Do not select a fund only because its recent return is 15% or more.
Fund consistency and downside management are equally important.

» How I would invest Rs.5 lakh

If you are comfortable with market fluctuations and the investment horizon is long, you can invest gradually through STP over several months if you are concerned about entering the market at one time.

If the money is needed within 3–5 years, I would not target 12–15% by taking aggressive equity risk.

» Final Insights

As an Investment professional and AMFI-Registered MFD, I would first assess your existing MF holdings before adding new schemes. This avoids unnecessary duplication and overlap.

If you share your age, investment period, whether Rs.5 lakh is lump sum or SIP, and your existing MF holdings, I can suggest a more suitable asset allocation and fund-category combination.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 10, 2026

Asked by Anonymous - Sep 10, 2026
Money
I have 15 lacs to Lumsum investment for my daughters higher education.I want to invest in STP in 3 funds .One hybrid Fund which has 15l value and from that STP to two fund Any multicap or Large and Midcap Fund .Please suggest ? Any other Idea will also appriciate.Thanks
Ans: Your approach of using STP for your daughters higher education goal is a good way to move a lump sum into equity gradually. The main point is to match the asset allocation with the time left for the education goal.

» Suggested structure

Keep the Rs.15 lakh initially in a suitable hybrid fund.
Use STP from the hybrid fund into two diversified equity categories.
A combination of Multi Cap and Large & Mid Cap can work well.
You need not use too many funds. Three funds are enough for this goal.

For example:

Hybrid Fund – Rs.15 lakh initially
Multi Cap Fund – STP destination
Large & Mid Cap Fund – STP destination

» How to use STP

I would prefer a systematic STP over a very short period.

If the education goal is more than 5 years away, equity allocation can be meaningful.
The Rs.15 lakh can be shifted gradually over around 12 months.
You can divide the STP between the two equity categories.
Avoid changing funds frequently based on short-term market movements.

STP is mainly useful for managing entry risk. It does not remove market risk.

» Do not ignore the education timeline

This is the most important part.

If higher education is:

More than 10 years away – higher equity allocation can be considered.
Around 5–10 years away – balanced equity and hybrid allocation may be better.
Less than 5 years away – avoid taking high equity risk with the entire corpus.

As the education date comes closer, gradually move the required amount towards safer investments. This protects the money already created.

» Multi Cap vs Large & Mid Cap

Both categories can complement each other.

Multi Cap gives exposure across large, mid and small companies.
Large & Mid Cap gives a relatively stronger focus on large and mid-sized companies.
Combining both can create some overlap, so the portfolio should be reviewed periodically.

I would not select funds only based on the latest 1-year or 3-year returns. Fund quality, portfolio consistency, risk management and long-term performance matter more.

» One alternative idea

Instead of keeping the complete Rs.15 lakh in one hybrid fund, you can also consider a two-stage approach.

Keep the amount in a suitable hybrid/debt-oriented allocation initially.
Start STP into diversified equity funds.
Once the required equity allocation is reached, stop the STP.
Continue monitoring the overall portfolio rather than continuously adding new funds.

This keeps the portfolio simple and easier to manage.

» 360-degree education planning

The Rs.15 lakh should not be viewed separately.

Also consider:

Current age of your daughter.
Expected year of higher education.
India or overseas education.
Present education cost and future cost.
Other investments already available for this goal.
Your monthly SIP capacity.
Emergency fund and adequate insurance.
A separate safe corpus as the education date gets closer.

If the goal is 8–12 years away, this Rs.15 lakh can become a strong foundation. Regular SIPs along with it can make the education corpus much stronger.

» Final Insights

Your basic STP idea is sensible. I would prefer a simple 3-fund structure rather than holding many schemes.

The exact equity allocation and STP period should depend mainly on your daughters age and when the higher education money will actually be required.

As an AMFI-Registered MFD, I would also suggest reviewing this goal at least once a year and reducing equity exposure as the goal approaches.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
T S Khurana

T S Khurana  |572 Answers  |Ask -

Tax Expert - Answered on Sep 07, 2026

Money
a. An apartment in a four in one building was purchased by me on 18/02/1991 at a cost of Rs.2,60,000/- b. All the four owners of the building decided to go for redevelopment and Joint Development agreement was done with a builder on 12/02/2019. c. As per agreement total 6 flats will be constructed of which four for original owners and two for the builder. d. The vacant possession of the building was handed over to builder only during June 2019. e. Building demolition permission was obtained on 5/08/2019 f. New Building approval was given on 9/10/2020. ( The delay was due to Coastal Zone permission and new FSI rule approval ) g. Completion certificate was obtained on 8/3/2023. h. There was nil monetary transaction between owners and builder. i. The builder sold his flats for RS.1.04 crore and Rs.1.02 crores respectively 0n 30th June 2023.(ie.on getting completion certificate) j. Now I propose to sell my flat for 1.125 crore. BASIC DETAILS : I. I have Pension income, Interest from deposits and Dividend income from my Bank’s shares and am a regular IT payer. II. I have two house properties of which the above is one and another is a dilapidated house in a remote village with taxable value of Rs.35/- III. I was showing the house property income of Rs.35/- under ITR2 till assessment year 2020-21. IV. On demolition of the above flat in 2019, I was showing the village property only as self-occupied with NIL income under ITR1. V. This continued till assessment year 2025-26. ( It means for assessment years 2023-24,2024-25 and 2025-26 the reconstructed property was omitted to be shown in IT. The effect on taxation is Rs.11/- per year considering the village property’s taxable value) VI. This year I have shown both the properties as self-occupied in my IT return Advise sought: A. How to ascertain the value of property on the date of completion certificate? B. The property not being alienated, the capital gains should be “NIL” as on 2023. But in 2023-24 IT return it was not brought out. What is course correction for it now? C. What will be the Capital gain on sale of this property now - may be during September?
Ans: Relavent dates and figures are :
01. Purchase Price (1991) Rs.2.60 (L).
02. Expected Sale Price (2026) Rs.112.50 (L).
03. No Cost/Expenses were incurred during 12.02.2019 to 2026 (expected Sale date).
04. You will have to pay LTCG based on these figures.
05 (a). TAX PLANNING : You should get a Valuation Certificate from Architect, about the value of your Flat as on 01.04.2001. This can be treated as Cost of your property/flat in 2001. Indexation benefit may be taken from this date & this value.
05 (b). Since you occupied this Flat during the period from 2001 (date of valuation) till June-2019, you can claim Maintenance & Renovation Cost during this period, if any. This shall reduce your tax liability.
05 (c). Cost or Value an on date of completion certificate, is not relevant in this case. Cost of newly build flat shall be considered as explained in above points.
06. LTCG shall be taxed at rate of 12.50% without Indexation or @ 20% with Indexation.
07. Exemption can be claimed u/s 54 if you purchase another Residential unit, with in specified time. You can also purchase Capital Gain Bonds up to Rs.50.00 (L) to save Tax.
08. You are most Welcome to write for any further details or points, if required. Thanks.
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 03, 2026
Money
HI I am 47 years old with Monthly expenses of Rs 40000 , i would like to know how much retirement corpus would i require at age of 60 so that it lasts till age 85 also the opening Retirement corpus at 60 and closing Corpus at 85 should almost be same , as i would like to transfer it yo me daughter, i would like to know should i factor 8% food inflation as that will be major expense factor also factor 6% intrest on investment. Whats is the inflation rate should i assume , in which mutual fund should i invest for Rs 50000 monthly investment. How much money should i park for medical expenses or emergency
Ans: You have started this planning at a good age. With 13 years left, you have useful time to build the corpus.

» Your retirement target

– You are currently 47 years old.

– Your present monthly expense is Rs.40,000.

– You plan to retire at age 60.

– You want the corpus to support you until age 85.

– You also want the corpus to remain almost intact.

– This is a higher target than normal retirement planning.

– Your aim is also to pass the corpus to your daughter.

» Inflation assumption

– I would not use 8% food inflation for the entire retirement budget.

– Food is only one part of your total expenses.

– Medical, housing, travel and other costs behave differently.

– For long-term planning, 6% overall inflation is a reasonable assumption.

– However, medical inflation can be higher than general inflation.

– So, keep a separate medical reserve.

» Your expense at age 60

– Your present Rs.40,000 monthly expense will rise substantially by age 60.

– At 6% inflation, it can become roughly Rs.85,000 monthly.

– This should be your starting retirement expense.

– You should review this estimate again around age 58.

» Retirement corpus required

– You have given an important condition.

– You want the corpus at 85 to remain almost equal.

– Therefore, a normal retirement corpus calculation is not enough.

– Assuming only 6% investment return creates a difficult situation.

– Your withdrawal also rises with inflation.

– If return and inflation are both around 6%, preservation becomes difficult.

– Under those assumptions, I would target around Rs.3.15 crore at age 60.

– This is an approximate planning figure.

– It is not a guaranteed required amount.

– A higher return assumption can reduce the required starting corpus.

– But I would not depend on high returns for retirement planning.

» Why Rs.3.15 crore is a safer target

– Your first retirement-year expense could be around Rs.85,000 monthly.

– Expenses would then rise every year.

– You also want money remaining at age 85.

– Therefore, the corpus must support withdrawals and continue growing.

– Rs.3.15 crore gives you a better starting target.

– Still, market returns will not come evenly every year.

– Hence, actual results can differ materially.

» Your Rs.50,000 monthly investment

– Rs.50,000 monthly is a good starting contribution.

– However, it may not be enough by itself for Rs.3.15 crore.

– You have 13 years before retirement.

– Therefore, annual increases in your investment are very important.

– Try increasing the monthly investment whenever your income rises.

– Even a gradual increase can make a major difference.

– Existing savings, PF, gratuity and other retirement benefits can also help.

» Mutual fund strategy

– Do not put the entire Rs.50,000 into one mutual fund.

– At your age, you still have a long investment period.

– A diversified actively managed equity portfolio can be considered.

– You can use large-cap oriented funds for the core portion.

– A flexi-cap oriented fund can provide wider diversification.

– A limited mid-cap allocation can add growth potential.

– Avoid excessive small-cap exposure for retirement money.

– Your portfolio should gradually become safer after age 55.

» Suggested structure for Rs.50,000 monthly

– Rs.20,000 in a diversified flexi-cap oriented fund.

– Rs.15,000 in a large-cap oriented actively managed fund.

– Rs.10,000 in a mid-cap oriented fund.

– Rs.5,000 in a balanced or equity-oriented hybrid fund.

– This is only a starting structure.

– Your existing investments should be checked before finalising this allocation.

» Why actively managed funds can help

– Active fund managers can change portfolios based on market conditions.

– They can reduce exposure to weaker companies.

– They can also identify changing business opportunities.

– This flexibility can be useful over a 13-year period.

– However, fund selection and monitoring remain important.

– Past performance alone should never decide fund selection.

» Emergency fund

– Keep at least 9 to 12 months of household expenses separately.

– For you, I would initially target around Rs.5 lakh.

– Keep this money in highly liquid and low-risk avenues.

– Do not count your equity mutual funds as emergency money.

– This reserve should not be used for routine investing.

» Medical reserve

– Medical expenses need separate planning.

– Do not depend only on your normal retirement corpus.

– Build a dedicated medical reserve before retirement.

– I would initially target Rs.10-15 lakh as a separate reserve.

– This should be reviewed closer to age 60.

– Your health insurance coverage should also be reviewed regularly.

– Medical inflation can be much higher than normal inflation.

» Protecting the corpus after age 60

– This is perhaps the most important part of your plan.

– Do not keep the entire retirement corpus in equity.

– Keep several years of expenses in safer investments.

– Keep the remaining portion invested for long-term growth.

– This can reduce the need to sell equity during market falls.

– Rebalance the portfolio periodically.

» Your daughter and inheritance goal

– Your objective is very clear.

– You want to enjoy retirement and still leave money behind.

– This requires controlled withdrawals.

– Avoid treating the entire corpus as spending money.

– Maintain a separate inheritance mindset.

– Estate planning should also be completed before retirement.

– Nominees should be updated across investments and accounts.

– A proper Will can make the transfer much easier.

» One important improvement

– Do not wait until age 60 to reach the target.

– Start building the retirement corpus aggressively now.

– Increase your Rs.50,000 SIP every year.

– Any bonus or additional income can partly go towards retirement.

– At around age 55, reassess the entire retirement plan.

– At age 58, prepare the final retirement-income strategy.

» Final Insights

– Your Rs.3.15 crore target at age 60 is a useful planning benchmark.

– This assumes around 6% return and 6% inflation.

– It also considers your wish to retain the corpus at 85.

– I would not use 8% food inflation for all expenses.

– Use 6% general inflation for initial planning.

– Keep medical expenses separately because they can rise faster.

– Rs.50,000 monthly investing is a good beginning.

– Increasing this SIP every year is more important.

– Your investment strategy should become safer near retirement.

– The goal is not just Rs.3.15 crore.

– The real goal is sustainable income plus a meaningful inheritance.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 03, 2026
Money
Ant thing we can purchase from market by knowing the rate even for safety pin. You can purchase from anywhere in indie online the noted prices for share. Why the MF units are not possible to buy by seeing the prize or why it should not be online varying price for day. Not showing the price, Asset management can cheat the customer. SEBI is ineffective for controlling this cheating
Ans: Your question is very practical. The difference comes from how shares and mutual funds are structured.

» Why share prices are visible instantly

– A share is traded directly between buyers and sellers on a stock exchange.

– The exchange matches buy and sell orders continuously.

– Therefore, you can see the latest traded price.

– You can place an order at that displayed market price.

– The price can change many times during the day.

» Why mutual funds work differently

– A mutual fund unit is not traded like an ordinary share.

– You buy or redeem units from the mutual fund.

– The fund collects money from many investors.

– It then invests that money in securities.

– The value of all those investments changes during the day.

– The fund calculates its Net Asset Value, called NAV.

– NAV represents the value of one mutual fund unit.

– NAV is normally calculated after the market closes.

– Therefore, there is no continuously traded MF unit price.

» This does not mean the price is hidden

– Mutual fund NAVs are publicly available.

– The NAV is disclosed for every business day.

– Your transaction also receives units based on applicable NAV rules.

– The applicable NAV depends on transaction timing and fund realisation rules.

– Therefore, the NAV is not controlled by an individual agent.

» Why you cannot buy at the displayed NAV

– Suppose today's NAV is Rs.100.

– You cannot simply place an order at Rs.100.

– The final applicable NAV depends on the transaction rules.

– The fund must also receive the required money.

– This prevents investors from knowing the exact NAV beforehand.

– It also ensures fair treatment among all investors.

» Can an AMC cheat by changing NAV?

– An AMC cannot simply choose an arbitrary NAV.

– NAV is based on the value of underlying investments.

– Listed securities generally use market-based prices for valuation.

– Other securities follow prescribed valuation methods.

– Fund accounting and valuation processes are subject to regulatory requirements.

– There are also audits, trustees and regulatory oversight.

– So, the system has several checks.

» Your concern about transparency is still important

– Investors should clearly see the NAV and transaction details.

– They should also receive confirmation of their units.

– You can independently check the NAV against official disclosures.

– Your account statement should show units, NAV and transaction dates.

– Any unexplained difference should be questioned immediately.

» Where investors sometimes get confused

– The NAV seen on an app is not always your transaction NAV.

– The displayed NAV may belong to the previous business day.

– Your purchase may receive the next applicable NAV.

– This depends on transaction timing and applicable rules.

– Bank realisation can also affect the applicable NAV.

– This can make the transaction appear different from your expectation.

» Why a share and MF cannot have identical pricing

– A share represents ownership in one company.

– An MF unit represents a proportionate interest in a portfolio.

– The portfolio may contain hundreds of securities.

– Its value must first be calculated.

– The unit NAV is then determined.

– Hence, MF pricing naturally works differently from stock exchange pricing.

» What would improve your confidence

– Always check the official NAV after the business day.

– Compare it with your transaction statement.

– Check the number of units allotted.

– Check the transaction date and applicable NAV date.

– Keep your account statements safely.

– Raise a written complaint if figures do not match.

– Escalate the matter if the AMC does not resolve it.

» Final Insights

– Your demand for better transparency is quite reasonable.

– However, absence of intraday MF pricing does not itself mean cheating.

– Shares and mutual funds have fundamentally different transaction mechanisms.

– Mutual fund NAV is calculated from the underlying portfolio value.

– The important point is whether the disclosed NAV is correctly calculated.

– If you find a specific mismatch, preserve the transaction evidence.

– Then the issue can be examined much more precisely.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 03, 2026

Money
Hi, I am presently working in CPSU and having 2.5 years remaining in my supperannuation. I have a in hand salary of Rs.1.3 Lac per month (after deduction of necessary contribution in PF, VPF and deduction of tentative monthly income tax). In addition to this, I had invested a sum of Rs.1.4 Cr in a HUDA property in Faridabad which is now around 6 Cr. I am alos getting a monthly pension ofRs. 21000/- (without D.A. component) per month from my parent department as I had submitted Technical Resignation from Govt. Service (MoR) and took permanent absorption in CPSU. I am also getting monthly rental income from a flat @Rs.20000/- per month. I have invested Rs. 60000 in mutual funds and Rs.5.5 Lacs in shares. My wife was also a Haryana Govt. Educationist (govt. job) and just superannuated from her job on 31.08.2026. She will be getting a monthly pension of Rs.75000/- per month in addition to her other retirement benefits. She also earns a monthly rental income from our parental house @8000/- per month. We both are covered under medical schemes of Haryana Govt. and me from MoR. My question is I want to purchase or built a house in GGN on around 200 sq. yd. (approx) plot and live there. Kindly guide me about our future on my email which is alredy provided please.
Ans: You have built a very strong financial base. Your retirement income also looks encouraging. The main decision is how much to spend on the Gurugram house.

» Your present financial position

– You have around 2.5 years of employment remaining.

– Your present take-home salary is around Rs.1.30 lakh monthly.

– You receive pension income of around Rs.21,000 monthly.

– You receive rental income of around Rs.20,000 monthly.

– Your wife has recently retired from Haryana Government service.

– Her expected pension is around Rs.75,000 monthly.

– She also receives rental income of around Rs.8,000 monthly.

– Your Faridabad property has appreciated substantially.

– Its present value is around Rs.6 crore.

– You also have mutual funds and shares.

– Your medical coverage through government schemes is another positive.

Overall, your retirement cash flow appears quite comfortable.

» The Gurugram house decision

– Buying or constructing your own house can be reasonable.

– This is different from buying property purely as an investment.

– You want to actually live there after retirement.

– Therefore, emotional and lifestyle factors are also important.

– Gurugram can provide good connectivity and healthcare facilities.

– However, avoid using the entire Rs.6 crore property value for construction.

– Your retirement security should remain the first priority.

» Set a maximum house budget

– Decide the total budget before selecting the plot.

– Include plot cost, construction cost and registration expenses.

– Also include interiors, furniture and other initial expenses.

– Keep a separate amount for future maintenance.

– I would avoid stretching the budget simply for a larger house.

– A comfortable house is enough for retirement years.

– Your retirement corpus should continue growing alongside the house purchase.

» How to fund the house

– Your employment income continues for another 2.5 years.

– Your wife's pension has already started.

– Your own pension also provides continuing cash flow.

– Rental income gives another stable monthly support.

– This reduces pressure on your investment portfolio.

– Ideally, use available surplus income for part of construction.

– Avoid selling the entire Faridabad property only for convenience.

– Also avoid taking a large loan close to retirement.

» What about the Faridabad property?

– This requires a separate strategic decision.

– You have created significant wealth through this property.

– However, it now represents a very large asset concentration.

– After retirement, this concentration deserves careful review.

– You may eventually consider monetising part of this asset.

– Any sale decision must consider capital gains and taxation.

– The money can then support retirement investments.

– Do not sell merely because Gurugram property prices look attractive.

» Retirement income planning

– Your combined monthly pension income should form the core income.

– Rental income provides an additional income stream.

– Your retirement corpus should ideally remain partly invested for growth.

– Keep a separate reserve for several years of regular expenses.

– This avoids selling investments during a market correction.

– Your post-retirement portfolio should become more balanced.

– Equity exposure can continue, but should match your risk capacity.

» Your mutual funds and shares

– Your equity investments currently appear relatively small.

– This is not necessarily a problem.

– Your property exposure is already quite substantial.

– Therefore, future financial investments can improve diversification.

– Consider gradually building a diversified mutual fund portfolio.

– Prefer actively managed funds suitable for your risk profile.

– Avoid investing large amounts suddenly after retirement.

– Review the portfolio at least once every year.

» Medical and emergency planning

– Your government medical coverage is a major support.

– Still, maintain a separate medical emergency reserve.

– Government coverage may have certain rules and limitations.

– Keep adequate liquidity for expenses not covered by the schemes.

– Also review whether your existing medical benefits continue after retirement.

– This should be confirmed before your retirement date.

» Before buying the 200 sq. yard plot

– Check the title and ownership documents carefully.

– Verify the approved land use and building permissions.

– Check road width and access to the property.

– Verify electricity, water and sewerage availability.

– Check local development and construction restrictions.

– Take independent legal verification before paying a major amount.

– For construction, obtain a realistic detailed cost estimate.

» A better retirement structure

– Keep your retirement house budget within a comfortable limit.

– Keep sufficient financial assets outside the property.

– Maintain adequate emergency liquidity.

– Continue some equity exposure for long-term inflation protection.

– Maintain suitable fixed-income investments for near-term requirements.

– Keep your pension and rental income for regular expenses.

– Use investment withdrawals only when genuinely required.

» One important point

– Your property wealth is excellent, but it is not regular income.

– Retirement planning should therefore focus on cash-flow sustainability.

– The new house will also become an illiquid asset.

– Hence, avoid having most of your wealth in properties.

– You already have a strong starting position for retirement.

– The next 2.5 years can be used very effectively.

– This period should focus on strengthening liquidity and retirement investments.

» Final Insights

– Yes, purchasing a Gurugram house can be financially possible for you.

– I would not reject the idea merely because retirement is near.

– But the house should be planned around your retirement finances.

– Do not allow the house to consume your retirement security.

– Your pensions and rental income provide a strong recurring income base.

– Your Faridabad property provides substantial financial flexibility.

– Your next step should be a complete retirement cash-flow plan.

– That plan should decide the maximum safe house budget first.

– Then decide whether to buy the plot or construct the house.

– With proper planning, you can enjoy the new home without financial stress.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 03, 2026

Asked by Anonymous - Sep 03, 2026
Money
From the Past 10 Years ,I am Holding the REGULAR MF -Frankline ELSS,ICICI Value Discovery Fund,HDFC Mid cap .Since this fund are perfoming well but my Concernt is my Return is Regulary Eaten away by the Commision by MF Agest since its a Regular.I feel in long term for next 10-15 years , I am Unnecassary Dimising my Return due to Commision. What can i Do Now to save the Commision, what best strategy can i use to Switch the Fund from R to Direct type.
Ans: » Your concern is valid

You have already held these investments for around 10 years.
Long-term discipline is a major strength in your portfolio.
Your concern about regular-plan costs is also reasonable.
However, switching blindly to direct plans may not improve your outcome.

» First, understand the commission

Regular plans include distribution expenses within their expense ratio.
This cost indirectly reduces the returns earned by investors.
The cost continues as long as you remain invested.
Direct plans have lower expenses because distribution costs are absent.
Therefore, direct plans can have a cost advantage over long periods.

» But regular plans provide useful services

A good MFD provides portfolio monitoring and transaction support.
They can help during market corrections and difficult periods.
They can also help maintain proper asset allocation.
Tax-related transaction planning can also be supported.
Behavioural mistakes can be reduced through proper guidance.
These services can be valuable during a 10-15 year journey.
So, the commission should be viewed against services received.

» Direct plan has some disadvantages

You must monitor the portfolio yourself.
You must decide when to rebalance your investments.
You must assess fund performance independently.
You must handle purchase, redemption and switch decisions.
Tax implications also need your attention.
Most importantly, you must avoid emotional decisions during market falls.
Lower cost alone does not guarantee better investor returns.

» Do not switch immediately

Your existing funds have already created substantial long-term capital gains.
Moving from regular to direct is not always a simple switch.
A switch is generally treated as a redemption and fresh purchase.
This can create capital gains tax consequences.
Exit loads may also apply in some situations.
Therefore, first calculate the tax and transaction impact.
Then compare that cost with future expense savings.

» A better strategy for you

Keep the existing investments under review first.
Check the current value and purchase cost of each holding.
Check the unrealised capital gains before making any switch.
Review whether each fund still suits your financial goals.
Avoid changing a good fund merely because it is regular.
Fund quality should come before expense ratio.

» For future investments

You can consider direct plans if you can manage everything yourself.
But do this only after understanding the responsibilities involved.
Alternatively, continue with regular plans through a good MFD.
The right choice depends on the service you actually receive.
Do not select direct plans only because the expense is lower.

» A possible transition approach

Do not convert the entire portfolio in one transaction.
First identify funds where the future cost saving is meaningful.
Check the capital gains and applicable taxation.
Consider future investments separately from existing holdings.
Existing units can be reviewed based on tax efficiency.
New investments can follow your chosen investment structure.
This gives you flexibility without disturbing the entire portfolio.

» Important point about your three funds

Since you have held them for around 10 years, review is essential.
Do not judge them only by their past performance.
Check consistency across different market cycles.
Check portfolio concentration and investment style.
Check whether the funds still fit your goals.
Also review whether you have too much exposure to mid-cap stocks.
Your overall asset allocation matters more than one fund.

» Tax point while switching

Equity mutual fund taxation must be considered before switching.
LTCG above Rs.1.25 lakh is currently taxed at 12.5%.
STCG on equity mutual funds is currently taxed at 20%.
A switch can therefore trigger taxable capital gains.
The tax cost should be compared with future expense savings.
This is especially important after a 10-year holding period.

» My preferred approach

First, prepare a complete portfolio statement.
Include purchase dates, purchase values and present values.
Identify the capital gains in each holding.
Review the portfolio allocation and fund suitability.
Then compare regular and direct versions of suitable funds.
After that, decide which holdings need action.
Avoid making a blanket switch simply to save commission.

» Final Insights

Your concern about long-term costs is financially sensible.
But cost saving should not be the only decision factor.
A good regular-plan relationship can provide meaningful value.
Direct plans can work well for disciplined and knowledgeable investors.
The best choice depends on your ability to manage the portfolio.
With a 10-15 year horizon, proper portfolio review is more important.
A phased approach can reduce unnecessary tax and investment disruption.
Your existing 10-year discipline gives you a strong base for the future.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Sep 01, 2026
Asked by Anonymous - Aug 08, 2026
Money
Sir 10 sal pahle maine apne bete sahil Sanjay Rathod ke nam se 30000 ki fd kar thi oh kaise vapas milega
Ans: » Good that you are checking this old FD now.

» If the FD was made 10 years ago in your sons name, it can still be traced.

– First find the FD receipt, if available.
– Check the bank or post office where it was opened.
– Carry your sons PAN, Aadhaar and bank details.
– If your son is now an adult, his presence may be required.
– If the FD was opened when he was a minor, old KYC records may help.
– Ask the branch to check the FD using his name and customer ID.
– The maturity amount depends on the original FD period and interest rate.
– If the FD matured earlier, the bank can confirm its present status.
– It may have been renewed automatically after maturity.
– It may also have been transferred to another deposit account.

» If the FD receipt is lost

– Do not worry. Banks can trace deposits through their records.
– Submit a written request to the branch.
– Provide the approximate opening year and FD amount.
– Give your sons full name and available KYC details.
– The bank can guide you about the claim process.

» Important point

– If your son is still a minor, the process differs.
– If he is now 18 or older, his KYC may need updating.
– If you tell me the bank name, I can explain the exact process.
– Also tell me whether your son is now above 18 years.

» Final Insights

– Rs.30,000 FD should not simply disappear because it is old.
– The key is identifying the bank and FD account.
– Please keep any old receipt or passbook safely.
– Do not pay anyone claiming they can recover the FD for you.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Aug 31, 2026

Asked by Anonymous - Aug 29, 2026
Money
Dear Sir, I have investments in the following mutual funds. I am planning to continue for the next 10 years. Please advise whether I can continue with them or should change to any other plan. 1 Nippon India Small Cap Fund - 10/2/2018 - 1000 2 Nippon India Large Cap Fund - 8/11/2017 - 1000 3 SBI Blue Chip Fund - 8/8/2018 - 2000 4 SBI Small Cap Fund - 8/2/2021 - 1000 5 Canara Robeco Large Cap Fund - 6/4/2023 - 3000 6 Mirae Asset Emerging Bluechip Fund - 8/5/2021 - 2000 7 Axis Small Cap Fund - 8/5/2021 - 2000 8 MIRAE ASSET ELSS TAX SAVER FUND 10/8/2022 - 2000 9. Parag Parikh Flexi Cap Fund - 7/6/2021 - 5000 Also I am planning to start a SIP of Rs 20000 in MF(FLEXI+LARGE+MID) for long run. I would appreciate your brilliant advice on the same.
Ans: Your existing SIP discipline is very good. You have also stayed invested for several years. That long-term approach is a strong positive.

» Current portfolio assessment

Your present SIP is around Rs.19,000 per month.
You have exposure to large-cap, mid-cap, small-cap and flexi-cap categories.
The main issue is not fund quality.
The bigger issue is significant overlap between categories and schemes.
You have three separate small-cap schemes.
You also have multiple large-cap oriented schemes.
This makes the portfolio more complicated than necessary.

» Small-cap allocation

You currently have three small-cap schemes.
This is more than required for most investors.
Small-cap funds can give strong long-term growth.
However, they can also fall sharply during weak markets.
Holding three small-cap schemes does not reduce this basic risk much.
I would prefer keeping only one small-cap fund.
The other small-cap SIPs can gradually be redirected.

» Large-cap allocation

You have exposure through multiple large-cap oriented schemes.
Holding several large-cap schemes creates considerable duplication.
One good large-cap allocation is generally enough.
I would consolidate this part of the portfolio.
This will make future monitoring much easier.

» Mid-cap allocation

Your existing emerging-blue-chip type exposure provides mid-cap exposure.
You can continue this allocation if its performance remains consistent.
However, adding another mid-cap fund may not be necessary.
One quality mid-cap fund is sufficient for your portfolio.

» Flexi-cap allocation

Your flexi-cap allocation is currently Rs.5,000 monthly.
This is a useful core holding for your long-term portfolio.
It provides flexibility across large, mid and small companies.
I would retain this allocation for the long term.
It can become one of your main portfolio components.

» ELSS allocation

Your tax-saving fund is also equity-oriented.
Continue it if you still need tax-saving investments.
If the tax benefit is no longer required, fresh SIPs can stop.
Existing investments can remain invested after their applicable lock-in.
Do not redeem only because the lock-in has ended.

» Proposed additional Rs.20,000 SIP

Your proposed Rs.20,000 SIP is a good step.

I would avoid splitting it equally between three categories.

A more balanced approach can be:

Flexi-cap: Rs.10,000
Large-cap: Rs.5,000
Mid-cap: Rs.5,000

This gives your new money a stronger core.

You already have enough small-cap exposure.

Therefore, I would not add another small-cap SIP now.

» Suggested portfolio structure

For the next ten years, I would aim for a simpler structure.

Flexi-cap: 35% to 40%
Large-cap: 25% to 30%
Mid-cap: 20% to 25%
Small-cap: 10% to 15%

Your exact allocation should depend on your age and financial goals.

If you are close to retirement, equity exposure needs more caution.

If your ten-year goal is genuinely long term, equity can remain meaningful.

» What I would change

Continue the existing flexi-cap SIP.
Continue one suitable large-cap allocation.
Continue one suitable mid-cap allocation.
Continue one suitable small-cap allocation.
Avoid adding more schemes unnecessarily.
Gradually redirect duplicate SIPs into your chosen core funds.
Review the portfolio once every year.
Avoid frequent switching based on one-year returns.

» Important point about old investments

Some of your investments are quite old.

That is actually a positive point.

Do not sell old investments merely to make the portfolio look neat.

First check their current value, capital gains and fund performance.

Then decide whether consolidation is worthwhile.

Unnecessary redemption can also create capital gains taxation.

For equity mutual funds, current taxation needs to be considered.

LTCG above Rs.1.25 lakh is taxed at 12.5%.

STCG is taxed at 20%.

» Ten-year investment approach

Ten years is a good investment horizon for equity mutual funds.

But the journey will not be smooth.

There can be periods of major market corrections.

During such periods, continuing SIPs is usually more useful than stopping them.

Your biggest advantage is your long investment horizon.

Use it properly.

» 360-degree review

Keep the number of equity schemes limited.
Avoid having multiple schemes in the same category.
Focus more on asset allocation than fund count.
Keep an emergency fund separately.
Maintain adequate health insurance.
Consider suitable life protection based on family dependency.
Keep short-term goals away from equity funds.
Gradually reduce equity risk as major goals approach.
Review fund performance, portfolio quality and consistency annually.
Do not chase last years top-performing funds.

» My overall view

Your portfolio has a good foundation.

The main improvement required is simplification.

I would not recommend adding many new schemes for the Rs.20,000 SIP.

Use the additional SIP to strengthen your core allocation.

Your existing portfolio can then be gradually consolidated.

With disciplined investing for ten years, your plan has good potential.

The key is consistency, proper allocation and annual review.

» Final Insights

Your portfolio does not require a complete overhaul.

It needs better consolidation and allocation.

The proposed Rs.20,000 SIP is a positive decision.

I would give priority to flexi-cap, large-cap and mid-cap.

Keep small-cap exposure limited to one suitable scheme.

This approach should make your portfolio easier to manage.

It should also reduce unnecessary duplication and concentration.

Best Regards,

K. Ramalingam, MBA, CFP,
AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Aug 29, 2026
Money
i am having happy family floater policy from oriental insurance company for medical insurance.The policy amount is Rs.8,00,000/-This policy covers my family .In my family,myself(AGE 66years),my wife (Age 51 years) And my son (AGE 21 years).Since 8 lakhs is not sufficient amount now a days for health coverage,I want to enhance the mediclaim policy amount.Since I am 66 years old,including my self in the same policy may increase premium amount.Please suggest me a good policy giving direction whether I should take 3 different policies individually for each one of us,or shall I make my wife and son a separate group.suggest me if I have take any separate policy for any type of critical illness like cancer?I was a smoke from my 22nd year to 50th year,i.e. from 1982 t0 2010.Since then I stopped smoking.But I was a heavy smoker smoking on average 20 cigarettes a day.If Iincrease our coverages to 15 lakhs rupees,is it sufficient.or any other suggestion.Similarly suggest a good policy and from whom I should take these policies.I can not enhance the existing policy as oriental insurance is not interested to enhance the policy amount because of certain claims which were there in this year and previous year. Thanks and Regards.
Ans: » Current position

Your concern is valid. At age 66, medical costs can rise sharply.

Your existing Rs.8 lakh cover should not be discontinued casually.

It has valuable continuity benefits.

Keep the existing Oriental Insurance policy active for now.
Do not cancel it before securing alternative coverage.
Your wife and son need not remain in the same floater.
Your age can significantly increase the floater premium.

» My preferred structure

I would consider a two-layer arrangement.

You: separate individual health policy.
Wife and son: separate family floater policy.
Existing Oriental policy: retain as an additional layer initially.

This structure gives better control over future premiums.

Your son is only 21, so his medical risk is relatively lower.

Your wife is 51, so a family floater can still work well.

For you, an individual policy is more suitable at age 66.

» Is Rs.15 lakh enough?

Rs.15 lakh is a reasonable minimum target today.

However, I would prefer higher overall protection.

Hospitalisation costs can become very high for major surgeries.

Cancer and prolonged treatment can also create large bills.

A practical structure could be:

Existing Rs.8 lakh policy as the base.
Separate individual cover for you.
Additional super top-up protection for the family.
Suitable cover for your wife and son through a floater.

This can provide stronger protection without a very high base premium.

» Why super top-up can help

A super top-up can provide additional protection above a chosen deductible.

It can be more economical than buying a very large base policy.

But please check the deductible carefully.

Also check whether the deductible works on annual aggregate claims.

This point is very important.

Do not buy a super top-up only because its premium looks cheap.

» Should you take separate policies?

For you, yes, I would seriously consider an individual policy.

For your wife and son, a floater can still work well.

There is no strong need to create three separate policies immediately.

The better structure depends on age and medical risk.

» About your previous smoking

You smoked heavily from age 22 to 50.

You have now stopped smoking for around 16 years.

That is a positive factor.

However, disclose your complete smoking history.

Do not hide it while purchasing a new policy.

The insurer may ask about smoking and previous medical conditions.

Your previous claims must also be disclosed correctly.

Non-disclosure can create problems during a future claim.

» Do you need a separate cancer policy?

I would not make a standalone critical illness policy your first priority.

First secure strong comprehensive health insurance.

Then consider critical illness protection if suitable.

Critical illness insurance generally pays a fixed amount after covered diagnosis.

It is different from regular health insurance.

Regular health insurance mainly covers eligible medical expenses.

Therefore, critical illness cover should be supplementary protection.

» Important conditions to check

Before selecting another policy, carefully check these points:

Room rent restrictions.
ICU restrictions.
Disease-wise sub-limits.
Co-payment requirements.
Pre-existing disease waiting period.
Specific disease waiting periods.
Maximum entry age.
Lifetime renewal availability.
Restoration benefit.
Day-care treatment coverage.
Non-medical expense coverage.
Claim settlement process.
Cashless hospital network.
Premium increases with age.

Avoid policies with heavy sub-limits.

Also be careful with compulsory co-payment at your age.

A lower premium may come with higher out-of-pocket expenses.

» What about portability?

Your existing policy has considerable value because of its continuity.

Health insurance portability can preserve certain accrued continuity benefits.

However, the new insurer will still perform medical underwriting.

Additional coverage can also have applicable waiting periods.

Therefore, do not surrender your existing policy casually.

» One important strategy

Since Oriental Insurance has declined enhancement, do not focus only on enhancement.

Instead, explore a fresh policy alongside the existing policy.

Your existing Rs.8 lakh cover can remain useful.

The new policy can provide additional protection.

This may be better than replacing the existing policy completely.

» What I would do in your case

My preference would be:

Continue the existing Rs.8 lakh Oriental policy.
Take a separate individual policy for yourself.
Take a separate family floater for your wife and son.
Add a suitable super top-up after checking conditions.
Consider critical illness protection separately.
Review the complete structure every year.

At age 66, continuity is extremely valuable.

Therefore, replacement should happen only after careful underwriting.

» One more important point

Because you mentioned previous claims, insurers may scrutinise your medical history.

Please obtain your complete claim history and current policy wording.

Also collect your recent medical reports.

This will help in getting accurate underwriting decisions.

Do not make decisions only from premium quotations.

» Final Insights

Your Rs.8 lakh cover should not be considered useless.

It is an important foundation because of its continuity.

Your next objective should be additional protection.

I would consider Rs.15 lakh as the minimum overall base protection.

However, I would prefer larger total protection through a super top-up.

For your age, policy conditions matter more than the cheapest premium.

For your wife and son, a floater can remain practical.

For yourself, an individual cover deserves serious consideration.

The final insurer should be selected after comparing policy wording.

Also compare exclusions, co-pay, waiting periods and underwriting.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in/

https://www.linkedin.com/in/ramalingamcfp/
(more)
Vivek

Vivek Lala  |327 Answers  |Ask -

Tax, MF Expert - Answered on Aug 29, 2026

Money
Hi, Myself Raj Banerjee aged 49 years. I am single. I work as IT professional and currently facing some challenges in job. My current annual expense in approximately 12L. I have small house and do not plan / aspire for any more real estate. Till now I have been able to accumulate 7.8cr all in Bank FD/savings, 90L in PF, 20L in PPF (still 7 years to mature), 25L in stocks and gold (50:50 split). I do not have any Life Insurance but have medical insurance for myself (5L retail policy + 8L corporate policy). Recently, I have started moving money from Bank to Mutual Fund monthly as below: ABSL MediumTerm Debt Direct Growth: 1L Parag Parikh Flexi Cap Direct Growth : 25K HDFC Flexi Cap Direct Growth: 25K Quant Multi Asset Direct Growth: 25K Nippon Multi Asset Direct Growth: 25K I plan to follow this till Bank FD falls to 2 cr, then in such case my tax out flow will be negligible in case of job loss and I can have expenses covered from interest. I am requesting help that assuming if I lose / leave job immediately is my approach looks okay or suggest better option so that I can generate income from investment and plan for living till 90 years.
Ans: Hello,

I’m glad to see that you understand the importance of personal finance and have built a strong financial position at the age of 49. Having said that, after reviewing the information shared, I believe there are a few important changes that can significantly improve the efficiency of your portfolio.

My observations:

1. Term Insurance
Based on your current financial position and the corpus you have already accumulated, I don’t believe term insurance is essential purely from a financial dependency perspective, provided your existing investments are sufficient to meet your family’s long-term requirements and there are no significant outstanding liabilities.

2. Current Asset Allocation
Your total liquid net worth is approximately ?9.15 crore, of which nearly 97% is invested in debt/liquid assets.

3. The biggest concern : excessive allocation to debt.
At your age and with your investment horizon, I believe the current debt allocation is too conservative.

A debt portfolio may reasonably generate around 7% over the long term, while your personal/real-life inflation could be closer to 8% or more, despite the official CPI inflation number being lower. This means that after adjusting for inflation, your purchasing power could actually decline over time.

The objective shouldn’t simply be preservation of the ?9.15 crore corpus, it should be preserving and growing its purchasing power for the next 30–40 years.

4. Retirement Readiness
Based on the numbers shared, your current annual withdrawal requirement is only around 1.3% of your total portfolio.

That is an extremely comfortable withdrawal rate. Subject to your future goals, liabilities and lifestyle requirements, I believe you are financially well positioned to consider retirement even today.

Changes I would recommend:

1. Maintain an emergency/liquidity corpus of approximately ?1 crore
Keep this in liquid/debt-oriented instruments for emergencies, near-term requirements and peace of mind.

The remaining corpus can be gradually moved towards a well-diversified portfolio of equity-oriented investments, including Mutual Funds, PMS and AIFs, depending on your risk appetite and suitability.

2. Re-evaluate your existing Mutual Fund portfolio
From the information shared, several of the funds appear to have been selected based on recommendations commonly seen on social media platforms.

There is nothing inherently wrong with that, but I would strongly recommend evaluating each fund based on portfolio quality, consistency, downside protection, fund manager track record, valuation, risk-adjusted returns and its role within the overall portfolio, rather than simply looking at past returns or popularity.

Appropriate changes can then be made wherever required.

3. Suggested allocation for the 7 crore Mutual Fund portfolio

As a starting framework, I would consider:

15% — Large & Mid Cap
15% — Multi Cap
15% — Mid Cap
15% — Small Cap
15% — Value
15% — Flexi/Value-oriented strategies
10% — Select thematic opportunities

The exact funds and final allocation should, of course, be decided after understanding your risk tolerance, investment horizon, cash-flow requirements and specific financial goals.

My overall view

You have already done the difficult part is building a substantial corpus.

The next stage is not about taking unnecessary risk. It is about putting the corpus to work efficiently while ensuring that it continues to grow faster than inflation.

With a 9.15 crore liquid corpus and a withdrawal requirement of only around 1.3%, I believe your financial position is extremely strong. The focus now should be on asset allocation, portfolio quality and long-term wealth preservation, rather than simply accumulating more money.

These are my preliminary observations based on the information shared. A detailed recommendation would require a deeper understanding of your goals, liabilities, risk profile, family requirements and existing investments.

Would be happy to hear your views and discuss the same further.

Do let me know your views on this on my website or on my LinkedIn profile, attaching the link :
https://www.slwealthsolutions.com/
- CA VIVEK LALA
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Aug 24, 2026

Asked by Anonymous - Aug 23, 2026
Money
Hello sir, I am Biswajit. I want to do SIP for my son's education and future. My son's name is Rajbir and he is four years old. I can do SIP of 15 to 20 thousand. Which app is better for SIP? Please create a good SIP portfolio so that I can understand how much minus I should invest in which fund. I hope I will get an answer to my question. Thank you very much.
Ans: – Biswajit, this is a very good goal for your four-year-old son Rajbir.

– Starting early gives you a long investment period.

– Your Rs.15,000–20,000 monthly SIP can build a strong education corpus.

– The key is consistency, not chasing the highest return.

» Suggested SIP Portfolio

For Rajbir, I would keep the portfolio mainly equity-oriented.

For a Rs.20,000 monthly SIP:

– Rs.8,000 – Flexi-cap equity fund

– Rs.6,000 – Large and mid-cap equity fund

– Rs.4,000 – Mid-cap equity fund

– Rs.2,000 – Balanced advantage fund

For a Rs.15,000 monthly SIP:

– Rs.6,000 – Flexi-cap equity fund

– Rs.4,500 – Large and mid-cap equity fund

– Rs.3,000 – Mid-cap equity fund

– Rs.1,500 – Balanced advantage fund

» Why This Combination

– Flexi-cap provides the main core of your portfolio.

– It can invest across different company sizes.

– Large and mid-cap funds provide a diversified growth approach.

– Mid-cap allocation can improve long-term growth potential.

– It can also have higher ups and downs.

– Balanced advantage gives some stability during market corrections.

– Four funds are enough for this SIP size.

– Avoid adding many funds without a clear reason.

» Investment Time Horizon

– Rajbir is currently four years old.

– His higher education may start around age 17 or 18.

– You therefore have around 13 to 14 years.

– This is a useful period for equity investments.

– Do not stop SIPs during market falls.

– Market corrections are normal in long-term investing.

» How To Use The SIP

– Start with Rs.15,000 if Rs.20,000 feels difficult.

– Increase the SIP whenever your income increases.

– A 5% to 10% yearly SIP increase can help greatly.

– Keep the SIP running through market ups and downs.

– Review the portfolio once every year.

– Avoid changing funds based on short-term performance.

» Important Step Before Education

– Around five years before Rajbir needs the money, reduce equity exposure.

– Start moving the required education amount towards safer investments.

– Do this gradually instead of making one large shift.

– This protects the education corpus from sudden market falls.

» Which App Is Better

– The app is less important than the investment process.

– Since you are investing through an AMFI-registered MFD, regular plans can be considered.

– Regular plans include professional support and portfolio monitoring.

– Your MFD can also help with nominee and documentation matters.

– Avoid selecting funds only because an app shows low costs.

– The lowest cost does not always mean the best overall solution.

» Do Not Over-Diversify

– Four funds are sufficient for your present SIP.

– Adding ten or fifteen funds will not improve diversification much.

– It can instead make portfolio monitoring difficult.

– Focus on fund quality, consistency and portfolio overlap.

» Protection For Rajbir's Goal

– Keep an emergency fund separately from this education SIP.

– Do not use the education portfolio for regular family expenses.

– Keep adequate life insurance for the earning parent.

– Maintain suitable family health insurance too.

– These protections help keep the SIP running during emergencies.

» Final Insights

– Rajbir has a useful time advantage because he is only four.

– Start with Rs.15,000 if that is comfortable today.

– Increase towards Rs.20,000 as your income improves.

– Keep equity exposure high during the early years.

– Gradually reduce risk before the education goal arrives.

– Stay disciplined and avoid reacting to market noise.

– This approach gives Rajbir a strong financial foundation for his future.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Aug 20, 2026
Asked by Anonymous - Aug 20, 2026
Money
Query for Experts: "I currently hold a 4-fund portfolio (Nippon India Small Cap, Kotak Emerging Equity, UTI Nifty200 Momentum 30, and Parag Parikh Flexi Cap). I am planning to add 1 extra fund dedicated strictly to capturing US market growth. For this 5th fund, I am deciding between Motilal Oswal Nasdaq 100 FoF and Motilal Oswal S&P 500 Index Fund. My dilemma comes down to this: * Existing Overlap in PPFC: Parag Parikh Flexi Cap already allocates roughly ~10.6% directly to US tech mega-caps (Alphabet ~4.6%, Meta ~2.2%, Amazon ~2.2%, Microsoft ~1.8%). * Motilal Oswal Nasdaq 100 FoF: Delivers high return potential through tech growth, but heavily duplicates the US mega-caps PPFC already owns and adds high volatility to my existing small/mid/momentum setup. * Motilal Oswal S&P 500 Index Fund: Delivers lower relative volatility, but expands diversification into 11 US sectors (banking, healthcare, industrials, energy) that PPFC does not touch. Given my setup of domestic growth funds plus PPFC, which of these two funds makes a better 5th addition for international exposure? Should I prioritize maximum growth via tech compounding (Nasdaq 100) or sector diversification and portfolio balance (S&P 500)?"
Ans: You have identified the real issue correctly. Your decision is not simply about which US index has given better returns. Your existing portfolio is already tilted towards aggressive growth, so the 5th allocation should ideally add something the portfolio currently lacks rather than increasing the same risk again.

» Your Existing Portfolio Is Already Growth Heavy

Looking at your four categories:

– Small-cap exposure gives you higher-growth potential, but also high volatility.

– Mid-cap exposure adds another aggressive growth component.

– Momentum strategy adds factor/style risk and can experience sharp reversals.

– Flexi-cap provides a more diversified core and also gives you some international exposure.

So your portfolio already has plenty of "return-seeking engines".

What it needs more is diversification.

That is an important distinction.

» Your Existing US Exposure Also Matters

You have correctly noticed that your flexi-cap holding already owns some large US companies.

Therefore, adding a technology-heavy US index can increase exposure to some of the same mega-cap businesses.

There is nothing automatically wrong with owning the same company through two funds.

The problem is unintended concentration.

You may think you are adding "international diversification", while actually increasing exposure to a small group of large technology/growth companies.

Always measure diversification by underlying holdings and sectors, not by the number of funds.

» Nasdaq-Type Exposure Is Not Really Broad US Diversification

A technology/growth-heavy US index can be a powerful growth allocation.

But I would view it more as a concentrated growth strategy than as complete US-market diversification.

It can have:

– High exposure to technology and technology-related businesses.

– Significant concentration in mega-cap companies.

– Higher valuation sensitivity.

– Higher volatility.

– Strong dependence on growth stocks continuing to perform.

This can produce excellent returns during favourable periods.

But it can also go through long phases of deep corrections and underperformance.

Your existing small-cap, mid-cap and momentum exposure already gives the portfolio considerable volatility.

Adding another aggressive growth component can amplify that.

» A Broad US Index Solves a Different Problem

A broad US large-company index gives exposure beyond technology.

It can include companies from:

– Healthcare.

– Financial services.

– Industrials.

– Consumer sectors.

– Energy.

– Utilities.

– Communication businesses.

– Technology.

So, between the two choices you mentioned, the broader US index would conceptually provide better sector diversification.

However, I still would not automatically recommend an index fund just because it provides broader exposure.

There are limitations to passive investing that should be understood.

» Why I Would Not Automatically Choose an Index Fund

An index fund simply follows a predefined index.

This creates some disadvantages:

– The fund manager cannot freely avoid an expensive company simply because its valuation appears stretched.

– Weak businesses can remain in the portfolio until index rules remove them.

– Market-cap weighting can result in increasingly large exposure to companies whose market values have already risen substantially.

– There is no active decision-making based on changing valuations or business fundamentals.

– The fund is designed to track the index, not protect your portfolio during difficult market conditions.

Low cost is useful, but low cost alone does not make an investment suitable.

» Active International Investing Has Some Advantages

Where suitable options are available and permitted for investment, an actively managed international allocation can provide more flexibility.

An active manager can potentially:

– Choose businesses based on fundamentals.

– Avoid certain companies despite their large index weight.

– Change sector allocation.

– Manage valuations.

– Look beyond the largest technology companies.

– Build a portfolio based on opportunities rather than index membership.

Of course, active management does not guarantee outperformance. Manager selection, portfolio quality, costs and consistency all matter.

But for an investor specifically seeking diversification rather than index replication, active management deserves consideration.

» Between Your Two Choices, Diversification Is More Logical Than More Tech

If I restrict the discussion only to the two options you mentioned, the broad US-market exposure fits your existing portfolio structure better than another concentrated technology/growth allocation.

Not because I expect it to generate higher returns.

Actually, the technology-heavy option may outperform strongly during some periods.

But you already have:

– Small-cap risk.

– Mid-cap risk.

– Momentum risk.

– Mega-cap US technology exposure through your flexi-cap holding.

So adding more technology concentration solves a problem you do not really have.

Adding broader sector exposure addresses diversification better.

» Do Not Build the Portfolio Around Maximum Return

Your question asks whether you should prioritise "maximum growth".

I would change that objective.

There is no way to know today whether technology, healthcare, financials, industrials or Indian small caps will generate the highest returns over the next 10–15 years.

If we knew that, diversification would not be required.

Diversification exists precisely because we do not know which asset, geography, sector or style will lead the next cycle.

So the objective should not be:

"How do I maximise returns?"

It should be:

"How do I build a portfolio where several different return drivers can work for me?"

» International Exposure Should Have a Defined Limit

Another important point: decide the allocation before selecting the fund.

Do not simply add a 5th SIP and allow international exposure to keep increasing.

First decide what percentage of your total equity portfolio you want outside India.

That percentage should consider:

– Your financial goals.

– Investment horizon.

– Risk capacity.

– Existing international exposure.

– Currency exposure.

– Indian equity allocation.

– Whether future expenses will be in India or overseas.

Then periodically rebalance back to that allocation.

Otherwise, if US markets perform very strongly for several years, international exposure can quietly become much larger than intended.

» Currency Is Another Source of Return and Risk

International investing adds another variable: INR versus the foreign currency.

If the rupee depreciates, it can help INR returns from foreign investments.

If currency movement goes the other way, it can reduce returns.

So the performance you experience in India will not necessarily be identical to what an investor in the US sees from the underlying market.

This is another reason international exposure should be treated as portfolio diversification rather than simply a higher-return strategy.

» Your Momentum Allocation Also Deserves Review

You already hold a passive momentum strategy.

That means part of your portfolio is following a rules-based factor approach.

Momentum can perform strongly when trends persist, but it can also experience sharp reversals when market leadership changes.

Combining:

– Small cap.

– Mid cap.

– Momentum.

– Technology-heavy international exposure.

can create a portfolio that looks diversified by fund names but is actually heavily tilted towards aggressive growth characteristics.

That is the portfolio-level risk I would focus on.

» Do Not Add a Fifth Fund Just Because Five Looks More Diversified

Four funds can be enough.

Five can also be enough.

Even three can sometimes be enough.

The number itself means very little.

A new fund should enter your portfolio only if it has a clear job.

In your case, that job would be:

"Provide meaningful international diversification that my existing portfolio does not already have."

Once you define the job that way, the decision becomes easier.

» Final Insights

Between concentrated US technology exposure and broad US sector exposure, I would lean conceptually towards broader diversification for your existing portfolio.

Your portfolio already has enough aggressive return drivers through small cap, mid cap and momentum, plus some US mega-cap exposure through your flexi-cap holding.

Adding another technology-heavy allocation can increase concentration rather than diversification.

However, I would not automatically choose an index fund either. Passive funds have limitations around valuation, concentration and lack of active security selection. A suitable actively managed international option can also be evaluated where available.

Most importantly, decide how much international exposure you actually need before selecting the product.

The best 5th fund is not necessarily the one with the highest expected return.

It is the one that gives your existing four-fund portfolio something genuinely different.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Aug 20, 2026
Money
My wife underwent TAVI procedure and our entire Insurance has been absorbed @ settlement of claim by Insurance company.Till October end, we dont have any insurance coverage. Being a retired banker, my insurance Company IBA is National Inaueance- thier TOA Medi Assust. My question is 1) whether any other ibsurance taken will cover both if us fron now inwards. 2) whether my wife will be covered from November and denied @ pre medical hospitalisation and surgery done
Ans: It is good that you are checking this now rather than waiting until November. After a major cardiac procedure, continuity of the existing health cover becomes very important. Your two questions also need to be treated separately: taking a new policy now, and restoration of cover under your existing retired-bankers group policy from November.

» Can You Take Another Health Insurance Policy Now?

– Yes, you can apply for another health insurance policy for yourself and your wife.

– But applying for insurance does not mean the insurer has to issue the policy on standard terms.

– Your wifes recent TAVI procedure and underlying heart condition must be fully disclosed in the proposal form.

– The new insurer will assess age, medical history, current health, medicines, previous hospitalisation and treatment records.

After underwriting, the insurer may:

– Accept the proposal.

– Ask for medical tests.

– Apply waiting periods as permitted.

– Offer cover with specific terms.

– Apply co-payment or other conditions, depending on the product.

– Or decline the proposal based on its underwriting policy.

So yes, you can apply. But do not assume that a newly purchased policy will immediately cover treatment connected with the recent heart condition.

» A New Policy Will Normally Treat the Heart Condition as Pre-Existing

This is very important.

Your wife has already undergone TAVI.

Therefore, when applying for a fresh policy, her cardiac condition, diagnosis, hospitalisation and surgery are already known medical history.

A fresh insurer will generally assess this as a pre-existing medical condition.

The insurer may cover the condition only after the applicable waiting period and subject to the policy terms and underwriting decision.

A new policy normally cannot be expected to pay retrospectively for treatment that happened before the policy started.

» Please Disclose Everything

Do not leave out the TAVI procedure because you are worried that the new insurer may reject the proposal.

Disclose:

– Heart condition.

– TAVI procedure.

– Hospitalisation dates.

– Current medication.

– Follow-up treatment.

– Other existing medical conditions.

– Previous insurance claims.

– Current insurance details.

If important medical information is hidden, a future claim can become much more difficult.

A policy issued after full disclosure is far more useful than a policy obtained by incomplete disclosure.

» Your Existing Cover From November Is a Different Matter

You mentioned that your current insurance limit has been fully utilised and the next coverage becomes available from November.

If this is the continuation/renewal of your existing retired-bankers group medical cover, your wifes situation can be different from taking a completely new retail health policy.

The important questions are:

– Is the policy continuing without a break?

– Is November the normal renewal date?

– Will the sum insured simply get refreshed on renewal?

– Does the existing policy continue to cover pre-existing diseases?

– Are there any restrictions after the sum insured has been exhausted?

– What are the rules for repeat treatment relating to the same cardiac condition?

– Is there any restoration/reinstatement benefit during the current policy year?

You need written clarification on these points.

» Previous TAVI Should Not Automatically Mean Future Claims Are Denied

If your wife remains continuously insured under the same group arrangement after renewal, the fact that she underwent TAVI earlier does not automatically mean that every future cardiac claim will be rejected.

But future treatment must satisfy the terms of the renewed policy.

For example, the insurer/administrator may examine whether a future hospitalisation is:

– A fresh medically necessary hospitalisation.

– Follow-up treatment.

– A complication of the earlier procedure.

– Part of the original hospitalisation episode.

– Covered under pre/post-hospitalisation provisions.

– Subject to any specific limit or exclusion.

Therefore, please do not rely only on a verbal statement saying "coverage starts again in November."

Get confirmation in writing.

» Pre and Post-Hospitalisation Need Special Attention

You asked whether your wife could be denied because the original hospitalisation and surgery happened before November.

This depends on what exactly you claim after November.

Expenses relating to a hospitalisation that occurred in the previous policy period do not automatically become a fresh claim simply because a new policy year starts.

Pre-hospitalisation and post-hospitalisation expenses are normally connected to the underlying admissible hospitalisation and are subject to the policy wording and specified time limits.

So, if the current sum insured has already been exhausted, do not assume that old treatment bills can simply be submitted again after the sum insured refreshes in November.

On the other hand, a genuinely new hospitalisation after renewal may need to be assessed separately under the renewed policy terms.

» Check Whether Any Restoration Benefit Exists Now

Before assuming that you have zero protection until October-end, check the present policy carefully.

Some health policies/group arrangements may provide restoration or reinstatement of sum insured after exhaustion, subject to conditions.

The restored amount may have restrictions regarding:

– Same illness.

– Same person.

– Related complications.

– Timing of restoration.

– Number of restorations.

– Maximum amount.

Your particular group policy may or may not provide this facility. So ask the insurer/administrator specifically rather than assuming there is no cover left.

» Portability or Migration Needs Careful Handling

If you are thinking about moving from the existing group cover to an individual/family health policy, ask about portability/migration possibilities and continuity benefits.

Previous continuous insurance history can sometimes help with waiting-period credits, subject to regulations, policy conditions and underwriting.

But after a major recent cardiac procedure, do not cancel or allow the existing cover to lapse merely because you have applied elsewhere.

First get the new policy issued and understand its conditions in writing.

Continuity of health insurance at your stage of life is extremely valuable.

» Consider Separate Policies for Husband and Wife

Depending on your ages and medical histories, also evaluate whether separate individual covers are more suitable than putting both of you under one shared family floater.

Why?

If one spouse has a major medical requirement, a shared sum insured can potentially get heavily utilised.

Separate covers can sometimes provide better segregation of medical risk.

But this depends on premium, underwriting, age, medical history and policy terms.

So compare the structure, not only the premium.

» Build a Medical Emergency Corpus Also

Your present experience shows why insurance alone should not be the only protection.

Even with health insurance, there can be:

– Co-payments.

– Non-medical expenses.

– Exclusions.

– Sub-limits.

– Treatment outside policy conditions.

– Periods when the available sum insured is exhausted.

As a retired person, maintaining a separate liquid medical emergency corpus can provide an additional layer of protection.

This money should remain relatively safe and easily accessible. It is not money to chase higher investment returns.

» What You Should Do Immediately

I would suggest the following:

– Get the current policy wording and November renewal terms.

– Ask the insurer/administrator in writing whether your wife will continue to be covered for the existing cardiac condition after renewal.

– Ask whether a fresh hospitalisation related to the heart condition after November will be covered.

– Ask whether any restoration/reinstatement benefit is available before October-end.

– Ask how post-hospitalisation expenses relating to the TAVI procedure will be handled.

– Apply for additional health insurance now rather than waiting until November, but disclose the complete medical history.

– Do not discontinue the existing group cover while exploring alternatives.

– Keep a separate liquid medical reserve.

Keep the written replies carefully. In health insurance, written policy terms and written insurer communication matter much more than verbal assurance from an agent or helpdesk.

» Final Insights

Yes, you and your wife can apply for another health insurance policy now. But because your wife has already undergone TAVI, a new insurer will consider her existing cardiac history during underwriting. Immediate unrestricted coverage for that condition should not be assumed.

Regarding your existing retired-bankers cover, if it renews continuously in November, your wifes previous TAVI does not by itself mean that she loses all future coverage. But whether a future cardiac treatment is payable will depend on the renewed policy terms, continuity of coverage and nature of the future claim.

Most importantly, do not allow the present policy to lapse while searching for another option.

Maintain continuity, explore additional coverage with full disclosure and create a separate medical emergency corpus. After experiencing one major claim that exhausted the available cover, having these multiple layers of protection becomes particularly important.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Aug 20, 2026
Asked by Anonymous - Apr 23, 2026
Money
Sir , am 42 yearsbold wirh child 6 years of age. Ibhave lost every penny because of blindly believing in family and signing on the cheques. Still on my name one chit fund is there, whichm am not paying, but they are behind me which is atounf 50 lakh Now,am earning 1.5 lakh per month. I need ro take care of house hold ,rent 20k , child education . Till now i didnt do any ivestement, i took lic policy for mychild for 1 lakh every year How ro better plan financially given the situation and come out of that chit fund too. Please suggest
Ans: The strongest point in your situation is that you still have an income of around Rs. 1.5 lakh per month at age 42. You have gone through a serious financial setback, but you still have earning years ahead of you. So the priority now should not be chasing high returns. It should be protecting your income, resolving the Rs. 50 lakh liability and rebuilding step by step.

» First Find Out Whether the Rs. 50 Lakh Is Legally Your Liability

This should be your first action.

You mentioned that the chit is in your name and you had signed cheques because you trusted family members.

Do not start paying Rs. 50 lakh simply because somebody is demanding it.

At the same time, do not ignore notices or payment demands.

Get the complete documents checked by a lawyer experienced in chit fund/recovery matters.

Ask for:

– Chit agreement.

– Amount originally subscribed.

– Amount already paid.

– Amount received, if any.

– Outstanding instalments.

– Interest and penalty calculation.

– Copies/details of cheques signed by you.

– Guarantor documents, if any.

– Notices already issued.

– Exact amount legally payable today.

– Whether any proceedings have already started.

Rs. 50 lakh is too large a liability to handle based on phone calls and verbal discussions.

» Do Not Sign Any More Blank Cheques or Documents

From now onwards, please change the way financial documents are handled.

– No blank signed cheques.

– No blank loan papers.

– No OTP sharing.

– No net-banking password sharing.

– No signing as guarantor without understanding the liability.

– No borrowing in your name for somebody else.

– No informal financial commitments based only on family trust.

Family relationship and financial responsibility are two separate matters.

Your signature can create a legal obligation even when you did not personally enjoy the money.

» Negotiation May Be Better Than Avoidance

If the lawyer confirms that the liability is genuinely yours, ignoring it will not solve the problem.

You may need to negotiate.

Explore whether the chit company is willing to consider:

– Restructured repayment.

– Longer repayment period.

– Reduction/waiver of some penalties, if possible.

– A documented settlement.

– Affordable monthly repayment.

Any settlement should be in writing.

Do not pay substantial amounts based only on an oral promise that the account will later be closed.

And do not take a very high-interest personal loan merely to make the chit problem disappear quickly. That may simply replace one difficult liability with another.

» Your Rs. 1.5 Lakh Income Needs a New Job

For the next few years, every rupee of income needs a purpose.

Your priorities should broadly be:

– Essential household expenses.

– Rent.

– Child education.

– Insurance protection.

– Emergency reserve.

– Legally required debt repayment.

– Long-term investment.

Right now, lifestyle upgrades should come much later.

This is temporary financial discipline, not permanent sacrifice.

» Build a Small Emergency Fund First

You mentioned that you have lost your savings.

So before aggressively investing, rebuild a basic emergency reserve.

Initially aim for a small buffer that can handle immediate unexpected expenses.

Then gradually build towards around 6 months of essential family expenses.

This money should remain liquid and relatively safe.

Why is this important?

Without an emergency fund, one medical bill, job interruption or family emergency can push you into another loan.

Your first investment is actually financial stability.

» Health Insurance Is Essential

Check whether you and your child have adequate health insurance.

If you are depending only on employer medical insurance, consider whether separate personal coverage is required.

A medical emergency should not force you to borrow when you are already handling a major liability.

» You Also Need Adequate Term Insurance

You have a 6-year-old child who depends on your income.

So adequate pure term life insurance is important.

The cover should consider:

– Family living expenses.

– Child education.

– Existing liabilities.

– Future financial responsibilities.

– Your current assets.

This becomes even more important because your present accumulated wealth is very low.

» Review the LIC Policy Separately

You mentioned paying around Rs. 1 lakh every year towards an LIC policy for your child.

Given your present financial situation, this deserves an immediate review.

Insurance and investment ideally should perform separate jobs.

You currently have:

– A possible Rs. 50 lakh liability.

– No meaningful investments.

– A young child.

– Need for emergency savings.

– Rent and household commitments.

In this situation, committing Rs. 1 lakh every year to an investment-cum-insurance policy may not necessarily be the most efficient use of your limited surplus.

But do not simply stop paying tomorrow.

First check:

– Policy type.

– Premium-paying term.

– Current surrender value.

– Paid-up value.

– Benefits promised.

– Number of premiums already paid.

– Financial impact of surrender.

If the policy is an investment-cum-insurance product and surrender is financially sensible after proper evaluation, you can consider surrendering it and redirecting suitable future surplus towards mutual funds based on your goals and risk profile.

But adequate pure life protection should be maintained separately.

» Your Child Still Has Time

Your child is only 6 years old.

That gives you a meaningful investment horizon before higher education.

Do not panic because you have not invested until now.

Once the emergency reserve and debt repayment structure are under control, you can start a separate SIP for the childs education.

For a long-term goal, suitable actively managed diversified equity mutual funds can be considered according to your risk profile.

You do not need a very large SIP from Day 1.

Start with an amount you can continue.

Increase it as your financial position improves.

Consistency is more important than starting with an unrealistic amount and stopping after six months.

» Retirement Cannot Be Ignored

At age 42, you also need to rebuild your own retirement corpus.

Your childs education is important.

But retirement is equally important because there is no education loan available for your retirement.

Once the immediate crisis is stabilised, maintain separate investment goals for:

– Child education.

– Retirement.

Do not mix both into one investment pool.

» Do Not Try to Recover Your Losses Quickly

This is a dangerous stage psychologically.

After losing substantial money, people sometimes think:

"I need to make this money back quickly."

That can lead to:

– Speculative stocks.

– Trading.

– Concentrated investments.

– Unregulated products.

– High-return promises.

– Borrowing to invest.

Please avoid this.

You do not need one big investment win.

You need many years of disciplined financial decisions.

At 42, you still have time for compounding to work. But only if you protect yourself from another major financial mistake.

» Your Recovery Should Happen in Stages

I would approach the next few years like this:

– First, establish the exact legal chit liability.

– Stop further financial commitments in your name for others.

– Control household expenses.

– Build a basic emergency reserve.

– Ensure adequate health and term insurance.

– Review the LIC child policy and surrender/redeploy only if suitable after checking the policy terms.

– Negotiate and structure the chit repayment if the liability is legally established.

– Start small goal-based mutual fund SIPs when cash flow permits.

– Increase SIPs as the debt burden reduces.

– Review the plan every year.

The sequence matters.

If you start investing aggressively while an expensive unresolved liability keeps growing, you may not actually be improving your net worth.

» Keep Your Financial Life Separate From Family

Considering what has already happened, this change is important.

Have your:

– Own bank account.

– Own cheque book.

– Own investment accounts.

– Own passwords and OTPs.

– Proper nominations.

– Personal record of all liabilities.

– Monthly tracking of income and expenses.

Helping family is a personal choice.

Giving somebody uncontrolled access to your financial identity is completely different.

» Final Insights

At age 42, with Rs. 1.5 lakh monthly income, your situation can still be rebuilt.

But your first goal is not mutual fund returns.

Your first goal is to find out whether the Rs. 50 lakh chit liability is genuinely and legally payable by you and, if yes, create a written repayment/settlement strategy.

At the same time, protect your monthly income. Build an emergency reserve, get adequate health and term insurance, review the Rs. 1 lakh annual LIC commitment, and avoid taking fresh high-cost debt.

Once this foundation is stable, start investing for your childs education and your retirement through separate goal-based portfolios. Start small if needed, then increase investments as your debt burden comes down.

You have lost money, but you have not lost your future earning capacity. At 42, that is your biggest financial asset today. Protect it and rebuild systematically.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Ramalingam

Ramalingam Kalirajan  |11480 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Aug 20, 2026
Money
Hi. i am 56 years old. My monthly income is 1.25 lac. i have 1 daughter. she is earning 50k p.m. my wife is a housewife. at present i have approx 75 lac invested in pf, ppf, sip & stock. Monthly expenditure around 40k. i want to retire after 2 years. Is it a good decision? And can i survive after my retirement agaisnt this investement of approx 75 lac.?
Ans: You are already in a fairly good position because your monthly income of Rs. 1.25 lakh is much higher than your present monthly expenditure of around Rs. 40,000. You also have about Rs. 75 lakh accumulated and another 2 years before the planned retirement.

But I would not say "yes, retire" based only on the Rs. 75 lakh figure. A few important things need to be checked first.

» Rs. 75 Lakh Is Not the Only Number That Matters

At retirement, the question is not simply:

"Is Rs. 75 lakh enough?"

The better question is:

"Can this corpus support you and your wife for the next 30+ years after considering inflation, medical costs and other goals?"

At age 58, you may have to plan until at least age 85–90.

That is a long retirement period.

So the corpus needs to provide income and also continue growing.

» Your Present Expenses Will Not Remain Rs. 40,000

Today your expenditure is around Rs. 40,000 per month.

But after retirement, this amount will keep increasing because of inflation.

Over a long retirement, even normal household expenses can become substantially higher.

Medical inflation can be even more challenging.

So retirement planning should not assume that Rs. 40,000 per month will remain sufficient throughout your life.

Your withdrawals will need to increase over time.

» Your Daughter Earning Is a Positive, But Do Not Depend on It

Your daughter earning Rs. 50,000 per month gives some comfort because she is financially independent.

But I would suggest planning your retirement without depending on her income.

Her income will eventually have its own responsibilities:

– Her personal expenses.

– Marriage, if applicable.

– Career changes.

– Her own family goals.

– Her investments.

If your retirement plan works independently of your daughters income, both you and she will have much greater financial freedom.

» Check Whether Daughter Related Goals Are Still Pending

Before deciding whether Rs. 75 lakh is enough, identify any major expenses still pending.

For example:

– Daughter related financial commitments.

– Large family commitments.

– Existing loans.

– Home renovation.

– Vehicle replacement.

– Medical expenses.

– Travel plans.

– Any other major one-time expenditure.

These should ideally not come from the corpus meant for your monthly retirement expenses.

If Rs. 75 lakh includes money required for these goals, then your actual retirement corpus is lower than Rs. 75 lakh.

» Your Wife Needs to Be Protected Too

Your retirement plan should not be designed only around your lifetime.

Your wife is financially dependent on the household income.

So ask another important question:

If something happens to you at age 65 or 70, will the remaining portfolio comfortably support your wife for the rest of her life?

This is why simply dividing Rs. 75 lakh by monthly expenses can give a false sense of security.

The portfolio needs longevity.

» Health Insurance Is Very Important Before Retirement

Please review your health insurance before leaving employment.

If your present medical cover comes mainly from your employer, do not assume it will continue after retirement.

You and your wife should ideally have suitable independent health insurance while you are still insurable on reasonable terms.

Also maintain a separate medical emergency corpus.

At this age, health-care planning is as important as retirement-income planning.

» Do Not Treat All Rs. 75 Lakh as One Corpus

You mentioned that the Rs. 75 lakh is spread across:

– PF.

– PPF.

– Mutual fund SIP investments.

– Stocks.

These investments have very different risk and liquidity characteristics.

So Rs. 75 lakh should not be treated as one homogeneous investment.

Your stock portfolio especially needs review before retirement.

A retirement corpus should not depend excessively on a few individual companies.

At the same time, moving everything into very conservative investments at retirement can create another problem: insufficient growth to fight inflation.

» You Still Need Equity After Retirement

Retirement does not mean all equity investments should be stopped.

At age 58, your investment horizon may still be 25–30 years.

A suitable portion of the portfolio can remain in well-selected actively managed diversified equity mutual funds for long-term growth.

The remaining portion can be allocated towards suitable lower-volatility and debt-oriented investments for near and medium-term requirements.

The exact percentage depends on your risk capacity, other income and required withdrawals.

This balance is important.

Too much equity creates volatility risk.

Too little equity creates inflation risk.

» Build Retirement Income in Buckets

A bucket structure can work well.

– Keep an emergency and medical reserve separately.

– Keep the next few years of required expenses in relatively stable and liquid investments.

– Keep medium-term requirements in suitable debt-oriented investments.

– Keep part of the long-term corpus in actively managed diversified equity mutual funds for inflation-beating growth potential.

Then review and rebalance periodically.

This can reduce the need to sell equity investments during a major market correction just to pay monthly household expenses.

» Your Next Two Years Are Very Valuable

You currently earn Rs. 1.25 lakh and spend around Rs. 40,000.

That means you have a healthy potential surplus.

Do not mentally retire today just because retirement is only two years away.

These two years can make your retirement substantially stronger.

Use this period to:

– Increase investments.

– Avoid unnecessary lifestyle inflation.

– Clear high-cost debt, if any.

– Build the medical reserve.

– Review health insurance.

– Reduce unsuitable stock concentration.

– Organise the retirement portfolio.

– Update nominations.

– Prepare a Will.

– Estimate post-retirement income from PF/pension or other sources.

This final accumulation period can be very powerful.

» Do Not Stop SIPs Just Because Retirement Is Near

If your present SIPs are linked to long-term goals and the underlying allocation is suitable, retirement itself is not a reason to stop them immediately.

In fact, your high current surplus gives you an opportunity to strengthen the retirement corpus over the next two years.

But the portfolio should be reviewed because investments suitable during the wealth-creation phase may not all remain suitable during the withdrawal phase.

» Test Retirement Before Actually Retiring

One practical idea.

For the next 12 months, behave financially as though you are already retired.

Try to live within the expected retirement budget.

Invest most of the remaining salary surplus.

Track every expense.

This will tell you whether Rs. 40,000 is really your sustainable monthly requirement or whether irregular expenses are being missed.

Annual insurance premiums, repairs, travel, gifts, medical expenses and vehicle expenses often do not show up properly in a simple monthly budget.

» Should You Retire After Two Years?

Based on the information given, I would say retirement at 58 looks possible to explore, but Rs. 75 lakh alone is not enough information to safely confirm it.

Before taking the final decision, we need to know:

– Corpus expected at age 58.

– Pension or other regular retirement income.

– Whether you own your residence without debt.

– Health insurance position.

– Any outstanding loans.

– Daughter related future commitments.

– Your wifes age.

– Current equity/debt allocation.

– Value and concentration of individual stocks.

– Expected major expenses after retirement.

– Whether Rs. 40,000 genuinely represents your complete lifestyle cost.

Once these are known, a proper retirement cash-flow assessment can tell you whether retirement at 58 is sustainable.

» Final Insights

You are not starting from a weak position.

You have Rs. 75 lakh already accumulated, a good monthly income, relatively controlled expenses and two more earning years available.

But I would not retire simply because Rs. 75 lakh appears large today.

The real challenge is making the money support two people for possibly 30+ years while expenses and medical costs keep rising.

Use the next two years aggressively to strengthen the corpus. Keep your daughters income outside your retirement calculations. Build a separate medical reserve, review health insurance, reduce unnecessary stock concentration and structure the retirement corpus across suitable short, medium and long-term buckets.

If this planning shows that your corpus can support inflation-adjusted expenses even under conservative assumptions, retiring at 58 can become a much more confident decision.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
(more)
Loading...Please wait!
DISCLAIMER: The content of this post by the expert is the personal view of the rediffGURU. Investment in securities market are subject to market risks. Read all the related document carefully before investing. The securities quoted are for illustration only and are not recommendatory. Users are advised to pursue the information provided by the rediffGURU only as a source of information and as a point of reference and to rely on their own judgement when making a decision. RediffGURUS is an intermediary as per India's Information Technology Act.

Close  
x