Need Expert Advice?Our Gurus Can Help
Harsh

Harsh Roongta  | Answer  |Ask -

Answered on Dec 24, 2019

Dipanjan Question by Dipanjan on Dec 24, 2019Hindi
Listen
Money

I had taken a loan from LIC HFL at a floating rate but for more than a few years now the rate is kept at 9.5 per cent despite reduction in the prime rate. All my mails have fallen on deaf ears. Is there any way I have get them to respond?

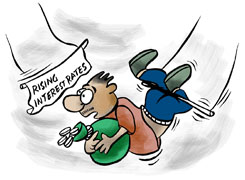
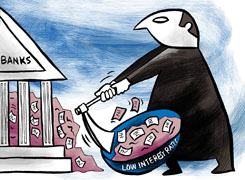
Ans: Welcome to the world of lenders in India where floating rate loans means that rate can only float upwards but seldom downwards in line with movement in market interest rates. Your best bet is to shift your loan to another lender which you can do if you have paid your EMIs on time.

DISCLAIMER: The content of this post by the expert is the personal view of the rediffGURU. Users are advised to pursue the information provided by the rediffGURU only as a source of information to be as a point of reference and to rely on their own judgement when making a decision.
Money

You may like to see similar questions and answers below

Ramalingam

Ramalingam Kalirajan  |11484 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Apr 19, 2025

Asked by Anonymous - Apr 18, 2025Hindi
Listen
Money
Dear sir, I have taken floating rate a plot loan from LIC HFL. Recently the ROI was increased from 8.75% to 8.85% immediately because of increase in bank rate. However the ROI is not reduced despite multiple repo rate changes recently. When asked the reply is - "We are yet to receive the updates from our CO with regard to changes in ROI. As soon as the ROI is changed automated message will be sent all customers."
Ans: You're absolutely right in expecting fairness when the repo rate goes down. Let me guide you step-by-step on what’s happening and what you can do next.


Understanding the Floating Rate Loan from LIC HFL

Your loan is linked to LIC HFL’s internal benchmark, not directly to RBI’s repo rate.


When RBI increases the repo rate, lenders are quick to increase your rate.


But when RBI reduces it, lenders often delay passing on the benefit.


This delay happens because LIC HFL’s Cost of Funds Based Lending Rate (COFBR) is not automatically updated.


COFBR is not as transparent or responsive as the external benchmark linked rates used by banks (like RLLR/EBLR).


Why LIC HFL May Not Reduce Your Rate Immediately

LIC HFL is an HFC (Housing Finance Company), not a bank.


They don’t follow the repo-linked lending rate (RLLR) system.


Their interest rates are based on internal policies and board decisions.


They may wait for quarterly reviews before passing on repo rate cuts.


Why the Communication Seems Delayed or Vague

You are told “waiting for CO update” – this is standard response.


In truth, they are buying time and not acting promptly.


Customers feel helpless because HFCs are not as strictly regulated as banks in this area.


What You Can Do Now: Action Steps

Write a formal email to the customer care, branch, and grievance officer. Request a clear explanation.


Ask them to share the latest COFBR and how your ROI is being calculated.


Use this format: “As a floating rate loan borrower, I am entitled to revised rate benefit. Kindly update my ROI in line with latest changes and share the effective date.”


If no proper response in 15 days, escalate it to NHB (National Housing Bank).


NHB is the regulator for HFCs like LIC HFL. You can file a complaint online.


Link: https://grids.nhbonline.org.in


Consider Switching the Loan to a Bank

If LIC HFL does not reduce rate, think of a loan balance transfer.


Switch to a repo-linked loan from a public or private sector bank.


These are directly linked to RBI’s repo rate. Very transparent.


You may have to pay small processing charges. But savings can be big.


Let a Certified Financial Planner help you calculate real benefit.


Check These Before Transferring

What’s the remaining tenure of your loan?


Is there any prepayment penalty? Usually none for floating loans.


Will new bank offer lower rate? Ask for a sanction letter before deciding.


Finally

LIC HFL may delay, but they cannot avoid revising your rate forever.


You are a responsible borrower. You deserve fair rate benefits too.


Keep your communication professional and written.


If they still delay, go ahead and move to a better lender.


Always have a Certified Financial Planner guide your debt and investments.


Best Regards,
 
K. Ramalingam, MBA, CFP,
 
Chief Financial Planner,
 
www.holisticinvestment.in
https://www.youtube.com/@HolisticInvestment

..Read more

Ramalingam

Ramalingam Kalirajan  |11484 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on May 19, 2025

Asked by Anonymous - May 18, 2025
Money
Sir we took a sbi global Ed-vantage education loan with collateral for 80lakh on May 2024. For 10.65.%for 15yrs. They said int rates are computerized pan India. So we trusted them. But after one year nd disbursement of 40lakh . But we got email saying interest is now 11.15% we checked. current rates it was 9.15 .%. we were shocked it made as to check what was the rate during our loan sanction time. It was same 9.15. we felt cheated . When we asked the bank they said they can't change that. Let's see what can be done for 0.5%increase . Trusting sbi nd not checking the rates was our fault. Now what's the remedy for us. Hope you can guide us. We will be grateful for your help.
Ans: You’ve done the right thing by revisiting and questioning the loan terms. It’s understandable to feel disappointed and betrayed. Many borrowers assume public banks will offer full transparency. But sadly, loan processes — even in SBI — are not always straightforward. Let’s explore your case from all angles and suggest clear remedies.


1. Understanding the Real Issue First
 

Your SBI education loan was sanctioned at 10.65% in May 2024.


Today, after disbursing Rs. 40 lakh, you’ve been told the new rate is 11.15%.


But the current advertised rate is only 9.15%.


This mismatch raises a key concern: Was your rate fixed or floating?


SBI Global Ed-Vantage loans are generally linked to EBLR (External Benchmark Lending Rate).


That means the interest rate must change as the RBI repo rate changes.


But the reality is, SBI often adds a “spread” or “premium” over the benchmark rate.


This spread is based on credit score, collateral, student profile, etc.


Even if repo goes down, SBI may increase spread, keeping final rate high.


And sadly, banks don’t disclose this clearly unless you ask.


2. What Might Have Happened in Your Case
 

SBI’s base rate (EBLR) may have been 9.15% during sanction.


But your rate was 10.65%, which means spread was 1.50%.


Now, repo may have dropped, but SBI raised the spread silently to 2.00%.


So your new rate is 9.15% + 2.00% = 11.15%.


This is how banks play with the spread behind the scenes.


It’s not illegal. But it is misleading if not explained upfront.


3. Your Mistake Was Only Trusting Without Verifying
 

It’s true — not checking the benchmark and spread is common.


Many assume SBI will give best possible rate.


But banks use “pan-India computerized” explanation to avoid individual discussions.


Now that you caught it, it’s time to take the right steps.


4. What You Can Do Immediately
 

First, send an official written complaint to SBI branch manager.


Ask for detailed loan sanction letter, annexure, and EBLR-linked rate calculation.


Request a written breakup: current repo rate + spread = your interest.


Ask for justification of why spread is 2.00% now.


Mention the advertised rate (9.15%) and ask why you didn’t get it.


Submit this via email and hard copy and ask for written reply.


5. If Bank Doesn’t Cooperate, Escalate in Stages
 

After 7 working days, if branch doesn’t reply, write to SBI Zonal Office.


You can get email and contact on SBI website under grievance redressal.


Still no help? Raise complaint to SBI Customer Care portal online.


Use this link: https://crcf.sbi.co.in/ccf/


Clearly mention the unfair spread hike, deviation from base rate, and lack of clarity.


Upload all documents, email chains, and screenshots.


You will get a complaint ID. Follow it regularly.


6. If Still No Resolution – Use RBI Ombudsman Route
 

Wait for 30 days from SBI complaint.


If no response or unsatisfactory reply, file online to RBI Banking Ombudsman.


Use this link: https://cms.rbi.org.in


Fill full complaint history, and attach copies.


You can highlight that loan was linked to repo rate but you were charged more.


RBI may take strict action if SBI is found wrong.


7. Optional But Powerful – RTI Filing
 

You can also file RTI to SBI Head Office.


Ask:


What was EBLR in May 2024?


What is the spread for Global Ed-Vantage loans for a profile like yours?


Why your loan is now at 11.15% while base rate is 9.15%?


File online here: https://rtionline.gov.in


Cost is Rs. 10. Takes 5 minutes. Use your name and bank account number.


SBI must reply in 30 days.


8. What to Avoid Now
 

Do not make fresh disbursement of the remaining Rs. 40 lakh unless clarified.


Don’t blindly continue EMI or interest payments without documents.


Don’t fall into trap of “switch to fixed rate” offers from bank.


That can trap you at high rates even when repo falls later.


And don’t assume you can’t fight – RBI is serious about customer complaints.


9. Is Loan Takeover Possible from Another Bank?
 

After first disbursement, loan takeover is hard.


Very few banks take over mid-way student loans.


But if issue continues, and rate remains high, you may explore NBFC options later.


They may allow takeover if collateral is strong.


But this should be Plan B, not immediate action.


10. What Can You Learn and Apply Ahead?
 

Always ask for base rate + spread breakdown during loan sanction.


Ask if rate is repo-linked or MCLR-linked or fixed.


Collect the signed loan agreement and annexure with these details.


Ask for email confirmation, not just verbal words.


And monitor repo and EBLR changes every quarter.


11. Financial Tip: Start Small SIP for Education Loan Buffer
 

Start a monthly SIP to build buffer for future EMIs.


In case interest rate continues rising, this corpus can help.


Use short-term debt fund or ultra short-term fund for this.


This will reduce dependence on fresh disbursement or bank help.


Finally
 

You’ve taken a bold and right step by verifying everything.


SBI has no right to quietly raise spreads without proper explanation.


You can fight this legally and fairly through written complaints and RTI.


Be persistent, polite, and professional.


Track everything and escalate stage by stage.


Your case can also become reference for many other parents and students.


Take this fight not just for you, but for every Indian borrower.

 
Best Regards,
 
K. Ramalingam, MBA, CFP,
 
Chief Financial Planner,
 
www.holisticinvestment.in
https://www.youtube.com/@HolisticInvestment

..Read more

Latest Questions
Ramalingam

Ramalingam Kalirajan  |11484 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Oct 13, 2026

Asked by Anonymous - Oct 10, 2026
Money
I am a 54 year old male working abroad. I have below investments. I have below investments so far: PPF 55 lakhs,EPF 36 lakhs, MF (total cumulative) 5.5 crores ,Employee superannuity+gratuity 14.5 lakhs, NPS 17 lakhs Monthly MF SIP ongoing 2 lakhs Company FD 10 lakhs Gold 16 lakhs. I am well covered in life insurance as well as medical insurance. My question is 1) My wife is getting a one time windfall of Rs .80 Lakhs as part of her share in her ancestral property. a)Pls guide me on how to invest this money b) what are the ways to save on tax eg. rbi relief bonds etc? c) if rbi relief bonds how much is the maximum limit d) beyond that limit where should i remaining balance?
Ans: Thank you for sharing your investment details. You have built a substantial investment portfolio through regular investing. The key now is to invest your wifes Rs.80 lakh windfall in a tax-efficient manner without adding unnecessary risk.

» Assessment of Your Current Portfolio

– Your existing investments are spread across mutual funds, EPF, PPF, NPS, company deposits and gold.

– Your mutual fund corpus is already substantial, with an ongoing SIP of Rs.2 lakh per month.

– Therefore, the entire windfall need not go into equity mutual funds. Your decision should depend on your retirement age, expected expenses, tax residency and the level of risk you are comfortable taking.

– Since you are working abroad, your residential status under Indian tax laws is important. The tax treatment of your investments and interest income can differ based on whether you qualify as a resident, NRI or RNOR.

» 1. How to Invest the Rs.80 Lakh Windfall

First, keep the money in your wifes name if she is the legal recipient of the ancestral property proceeds. Maintain proper documents showing the source of funds.

Consider dividing the money into three broad purposes:

– Safety and liquidity: Keep a suitable amount in bank deposits or other low-risk instruments for emergencies and expenses expected in the next few years.

– Stable income: Consider suitable government-backed or high-quality fixed-income options, after checking eligibility, taxation, lock-in and withdrawal rules.

– Long-term growth: Invest a portion in diversified, actively managed equity mutual funds if the money is not required for at least 7–10 years.

Since your existing mutual fund corpus is already Rs.5.5 crore, avoid putting the entire Rs.80 lakh into equity without reviewing your overall asset allocation. Your present equity exposure may already be sufficient for your retirement goals.

» 2. Can You Save Tax Through RBI Bonds?

It is important to distinguish between tax-saving investments and investments that offer safety or regular interest income.

RBI Floating Rate Savings Bonds are generally considered for investors seeking government-backed interest income. However, they are not a tax-saving instrument.

– Interest earned is taxable according to the applicable income tax rules.

– Investing in these bonds does not automatically provide a deduction under Section 80C.

– The bonds have a seven-year maturity period for ordinary individual investors, with premature encashment permitted only under specified conditions for eligible senior citizens.

– Interest rates are reset periodically, so the income may change over time.

Hence, these bonds can be considered for the safety and income portion of the portfolio, but not as a way to reduce tax on the windfall itself.

» 3. What Is the Maximum Investment Limit in RBI Bonds?

– There is no maximum investment limit in RBI Floating Rate Savings Bonds.

– However, these bonds are available to eligible resident individuals and HUFs. If your wife is an NRI, she would not be eligible to invest in these bonds under the current eligibility rules. Confirm her residential status before proceeding.

– The interest rate for July–December 2026 is 8.05% per annum, payable half-yearly. The rate is reset periodically.

– The maturity period is seven years, and liquidity is limited. Premature encashment is allowed only for eligible senior citizens after the specified lock-in period.

Therefore, these bonds may suit the stable-income portion of your wifes portfolio, provided she is eligible and can accept the lock-in.

» 4. Can You Save Capital Gains Tax on the Ancestral Property?

This is an important point to clarify before investing the money.

– If your wife received the property through inheritance, the inheritance itself is generally not taxable as income.

– However, if the ancestral property was sold and Rs.80 lakh represents her share of the sale proceeds, capital gains tax may arise. The taxable gain is not necessarily the entire amount received.

– Depending on the facts, Section 54EC capital gains bonds may offer tax relief when eligible long-term capital gains arise from the sale of land or a building.

– The maximum investment eligible for this exemption is Rs.50 lakh, subject to the applicable conditions and timelines. The investment must generally be made within six months of the transfer.

– These are different from RBI Floating Rate Savings Bonds. Section 54EC bonds are meant for eligible capital gains exemption, whereas RBI Floating Rate Savings Bonds provide taxable interest income.

If the property has already been sold, please check the sale date immediately. The deadline for claiming an exemption may be important.

» 5. Where Should You Invest the Remaining Amount?

If your wife is eligible for Section 54EC bonds and has sufficient eligible capital gains, up to Rs.50 lakh may be considered for that purpose.

The remaining amount can be allocated based on your financial goals.

– Bank deposits or other suitable fixed-income investments for short-term needs and capital safety.

– High-quality fixed-income instruments for the portion meant to provide stability.

– Diversified, actively managed equity mutual funds for long-term growth, if your overall portfolio review shows that additional equity exposure is appropriate.

Do not invest in a particular product only because it offers a tax benefit. Consider liquidity, taxation, maturity and the purpose of the investment.

» 6. My Final Assessment

Your family already has a strong investment base. At age 54, retirement planning, tax efficiency and asset allocation deserve more attention than simply maximising returns.

Before investing the Rs.80 lakh, please clarify these three points:

– Is the Rs.80 lakh received from an actual sale of ancestral property, or has your wife received the property itself as her share?

– Is your wife an Indian resident or an NRI for income-tax purposes?

– When was the property sold, if a sale has taken place?

These details will help determine whether capital gains tax applies, whether Section 54EC bonds are suitable, and how the remaining money can be invested efficiently.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
...Read more

Ramalingam

Ramalingam Kalirajan  |11484 Answers  |Ask -

Mutual Funds, Financial Planning Expert - Answered on Oct 13, 2026

Money
my father is 75 years old and my mother is 70 years old, she has stent in the heart, can you recommend which is the best health insurance policy for them. thanks
Ans: Thank you for sharing your parents details. Having health insurance at this age is important, especially when your mother has a heart stent.

» Health Insurance for Your Parents

– At 75 and 70 years, getting a new health insurance policy may be difficult. Premiums can also be high, and some insurers may not accept the application.

– Your fathers health condition and your mothers heart history will be considered during underwriting. Since your mother has a heart stent, the insurer may impose waiting periods, exclusions or other conditions.

– Do not choose a policy based on premium alone. Check the coverage, room rent limits, co-payment, disease-wise limits and claim conditions carefully.

» What You Should Check Before Buying

– Look for a senior citizen health insurance policy that accepts applicants of their ages and offers reasonable hospitalisation coverage.

– For your mother, disclose the heart stent procedure and all related medical details honestly. Ask the insurer in writing whether future cardiac treatment will be covered and from when.

– Check the co-payment clause. If the policy has a 20% co-payment, you may have to pay 20% of eligible hospital expenses yourself.

– Check pre-existing disease waiting periods. Existing heart conditions may not be covered immediately.

– Check whether the policy has limits on ICU charges, room rent, specific treatments or the total amount payable for certain illnesses.

» Consider These Alternatives

– If your parents already have health insurance, check whether it can be continued or enhanced. Keeping existing coverage may be more useful than buying a new policy.

– Check whether they have any employer-sponsored, government-sponsored or other eligible health coverage.

– If new insurance is unavailable or too costly, maintain a separate medical emergency fund. This will help meet hospital expenses not covered by insurance.

» My Assessment

At their ages, I would first check existing insurance and its continuation options. Then compare new policies based on actual coverage and exclusions.

For your mother, written confirmation about cardiac coverage is especially important. Do not assume that a policy will cover heart-related treatment simply because the insurer accepts her application.

Please share these three details for a more suitable assessment:

– Do your parents currently have any health insurance? If yes, what is the sum insured?

– Which city do they live in?

– Does your mother have any other medical conditions apart from the heart stent?

With these details, we can narrow down the available options and identify the most practical way to protect your parents from large medical expenses.

Best Regards,

K. Ramalingam, MBA, CFP,

AMFI-Registered MFD – ARN 4188

www.holisticinvestment.in

https://www.linkedin.com/in/ramalingamcfp/
...Read more

Krishna

Krishna Kumar  |429 Answers  |Ask -

Workplace Expert - Answered on Oct 12, 2026

Asked by Anonymous - Oct 12, 2026
Career
In my office, there are times when a colleague gets stuck with some work or makes a mistake, and I try to help them so that the work gets completed on time. Sometimes, I even put my own work aside to help them because I feel that we should support each other as a team. But when I am busy with my own tasks and need some help, the same colleagues are not always available. They may say they are busy or ask me to manage it myself. I don’t want to stop helping others because of this, as I feel it is important to maintain good relationships at work. At the same time, I sometimes feel that people take my helpful nature for granted, and my own work gets delayed because of it. I also worry that if I start refusing to help, my colleagues may think I have become selfish or uncooperative.
Ans: Dear

Very good question.

Few things let's get it clear. Each one is hired for a particular role and deliverables and they are paid for that.

You are hired first to do your work and deliverables assigned to you. Helping colleagues with their work, while letting your work aside is akin to not doing your responsibility.

My suggestion would be first focus on your work, if someone approaches you with a help and assistance for their work, you can provide them with guidance but do not end up doing their work.

If you are in the midst of your work and someone approaches you, you can politely yet firmly tell them that you are in mids if an important work and once done you will call them. DO NOT set aside your work for someone else. Remember you are working in a corporate world and not some social charitable organisation where any one can do everyone's work.

Hope this helps. All the best.

Warm Regards
KK

...Read more

DISCLAIMER: The content of this post by the expert is the personal view of the rediffGURU. Investment in securities market are subject to market risks. Read all the related document carefully before investing. The securities quoted are for illustration only and are not recommendatory. Users are advised to pursue the information provided by the rediffGURU only as a source of information and as a point of reference and to rely on their own judgement when making a decision. RediffGURUS is an intermediary as per India's Information Technology Act.

Close  

You haven't logged in yet. To ask a question, Please Log in below
Login

A verification OTP will be sent to this
Mobile Number / Email

Enter OTP
A 6 digit code has been sent to

Resend OTP in120seconds

Dear User, You have not registered yet. Please register by filling the fields below to get expert answers from our Gurus
Sign up

By signing up, you agree to our
Terms & Conditions and Privacy Policy

Already have an account?

Enter OTP
A 6 digit code has been sent to Mobile

Resend OTP in120seconds

x